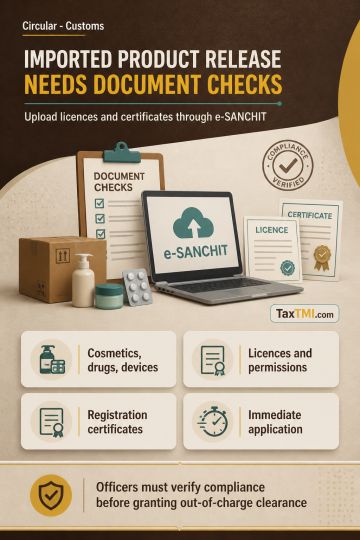
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
HC ruled that under CGST Act Section 54(11), the Department cannot withhold a refund sanctioned by the Appellate Authority based solely on potential revenue risk or alleged fraud. Without a pending appeal or review challenging the Appellate Authority's order, the Department must release the refund with statutory interest. The petitioner is authorized to seek further legal recourse if the refund is not credited by the specified date, affirming procedural safeguards against arbitrary administrative discretion in tax refund processes.
HC ruled that under CGST Act Section 54(11), the Department cannot withhold a refund sanctioned by the Appellate Authority based solely on potential revenue risk or alleged fraud. Without a pending appeal or review challenging the Appellate Authority's order, the Department must release the refund with statutory interest. The petitioner is authorized to seek further legal recourse if the refund is not credited by the specified date, affirming procedural safeguards against arbitrary administrative discretion in tax refund processes.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937