Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
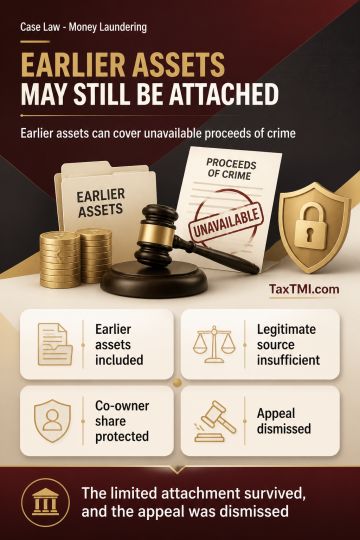
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
In a dispute concerning mesne profits, the ITAT addressed the classification of rental income from commercial premises. Analyzing divergent judicial perspectives, the tribunal referenced precedents from Kerala and Calcutta High Courts. Applying the principle of selecting the interpretation most favorable to the assessee, the tribunal determined that mesne profits constitute a capital receipt, thus rendering it non-taxable. Consequently, the tribunal allowed the assessee's appeals, establishing that the rental income from ground floor and basement commercial spaces should be treated as a capital receipt exempt from taxation.
In a dispute concerning mesne profits, the ITAT addressed the classification of rental income from commercial premises. Analyzing divergent judicial perspectives, the tribunal referenced precedents from Kerala and Calcutta High Courts. Applying the principle of selecting the interpretation most favorable to the assessee, the tribunal determined that mesne profits constitute a capital receipt, thus rendering it non-taxable. Consequently, the tribunal allowed the assessee's appeals, establishing that the rental income from ground floor and basement commercial spaces should be treated as a capital receipt exempt from taxation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918