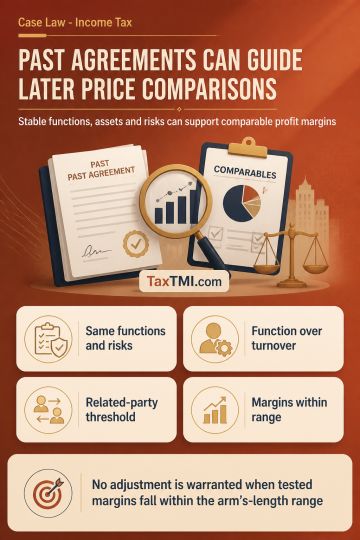
Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
In a dispute concerning mesne profits, the ITAT addressed the classification of rental income from commercial premises. Analyzing divergent judicial perspectives, the tribunal referenced precedents from Kerala and Calcutta High Courts. Applying the principle of selecting the interpretation most favorable to the assessee, the tribunal determined that mesne profits constitute a capital receipt, thus rendering it non-taxable. Consequently, the tribunal allowed the assessee's appeals, establishing that the rental income from ground floor and basement commercial spaces should be treated as a capital receipt exempt from taxation.
In a dispute concerning mesne profits, the ITAT addressed the classification of rental income from commercial premises. Analyzing divergent judicial perspectives, the tribunal referenced precedents from Kerala and Calcutta High Courts. Applying the principle of selecting the interpretation most favorable to the assessee, the tribunal determined that mesne profits constitute a capital receipt, thus rendering it non-taxable. Consequently, the tribunal allowed the assessee's appeals, establishing that the rental income from ground floor and basement commercial spaces should be treated as a capital receipt exempt from taxation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918