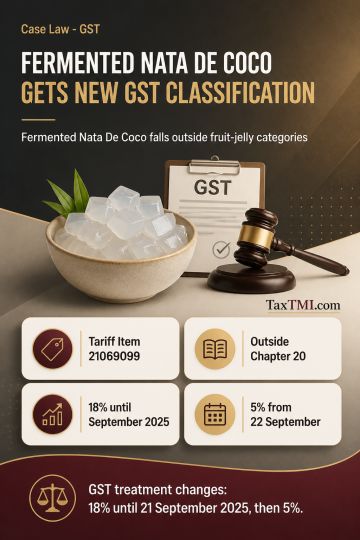
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
The HC set aside the impugned assessment order dated 28.08.2024 for AY 2019-2020 and consequential proceedings, applying precedent from MR. SAHULHAMEED case which established that assessees are entitled to service of notice under the modes prescribed in clauses (a), (b), and (c) of Section 169(1) of CGST Act, 2017. The petitioner was directed to submit a reply to the show cause notice within two weeks, after which respondent must provide a hearing opportunity before passing orders on merits. Any bank attachment made was ordered to be released. The petition was allowed.
The HC set aside the impugned assessment order dated 28.08.2024 for AY 2019-2020 and consequential proceedings, applying precedent from MR. SAHULHAMEED case which established that assessees are entitled to service of notice under the modes prescribed in clauses (a), (b), and (c) of Section 169(1) of CGST Act, 2017. The petitioner was directed to submit a reply to the show cause notice within two weeks, after which respondent must provide a hearing opportunity before passing orders on merits. Any bank attachment made was ordered to be released. The petition was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913