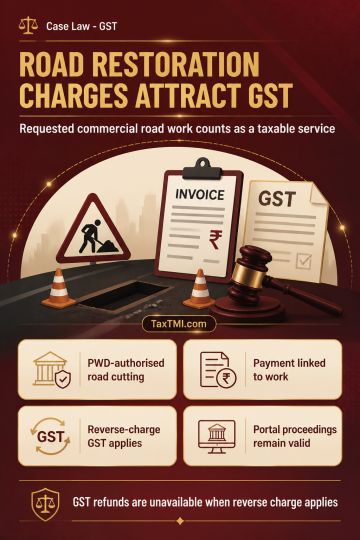
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
ITAT upheld the PCIT's order quashing the assessment under section 263 regarding TDS liability on payments to sales promoters claimed as reimbursements. The Tribunal found that the Assessing Officer failed to verify whether the transactions constituted genuine reimbursements as previously mandated. The AO merely accepted documentation without proper verification or reconciliation of whether sales promoters actually redistributed funds to retailers. Critical issues remained unaddressed, including how sales promoters were compensated and whether month-wise reconciliation statements existed to demonstrate actual disbursement to retailers. The ITAT directed the AO to verify disbursements by sales promoters against respective debit notes through proper reconciliation, dismissing the assessee's appeal.
ITAT upheld the PCIT's order quashing the assessment under section 263 regarding TDS liability on payments to sales promoters claimed as reimbursements. The Tribunal found that the Assessing Officer failed to verify whether the transactions constituted genuine reimbursements as previously mandated. The AO merely accepted documentation without proper verification or reconciliation of whether sales promoters actually redistributed funds to retailers. Critical issues remained unaddressed, including how sales promoters were compensated and whether month-wise reconciliation statements existed to demonstrate actual disbursement to retailers. The ITAT directed the AO to verify disbursements by sales promoters against respective debit notes through proper reconciliation, dismissing the assessee's appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927