Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
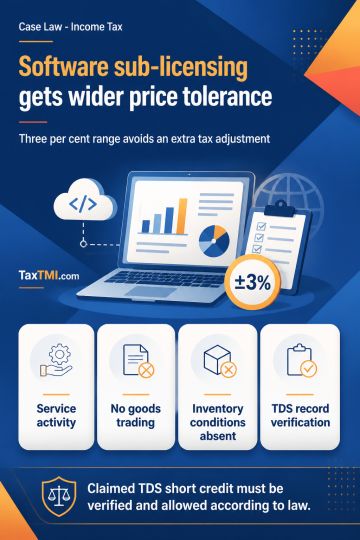
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
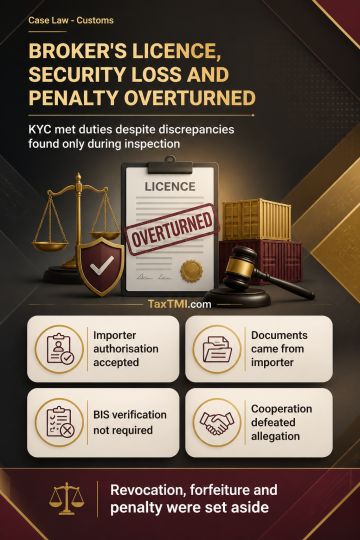
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
ITAT upheld CIT(A)'s decision allowing deduction of Finance Lease Rental Payments under section 37(1) as revenue expenditure. Revenue's appeal challenging depreciation allowance was deemed infructuous based on precedent from Karnataka HC regarding lessor's treatment of lease payments. The tribunal affirmed that finance lease rental payments qualify as allowable business expenditure rather than capital expenditure as initially classified by AO. The ruling maintains consistency with established judicial interpretation of lease payment characterization under Income Tax Act provisions. Revenue's appeal dismissed, confirming assessee's entitlement to claim rental payments as deductible business expense.
ITAT upheld CIT(A)'s decision allowing deduction of Finance Lease Rental Payments under section 37(1) as revenue expenditure. Revenue's appeal challenging depreciation allowance was deemed infructuous based on precedent from Karnataka HC regarding lessor's treatment of lease payments. The tribunal affirmed that finance lease rental payments qualify as allowable business expenditure rather than capital expenditure as initially classified by AO. The ruling maintains consistency with established judicial interpretation of lease payment characterization under Income Tax Act provisions. Revenue's appeal dismissed, confirming assessee's entitlement to claim rental payments as deductible business expense.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899