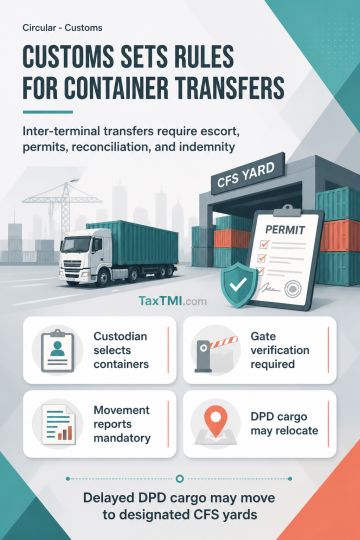
Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
Year-wise GST tax periods make composite show cause notices impermissible, requiring separate proceedings despite contrary non-jurisdictional preceden...
Taxpayer denied deduction under section 80IA as they failed to meet statutory requirements for infrastructure development projects. ITAT found that LMRCL, being a special purpose vehicle with 50:50 equity between Central and State governments, did not qualify as government authority/statutory body under section 80IA(4). Assessee's role was limited to tunnel construction per contract specifications. Regarding disallowance of technical service fees paid to Gulemark TPL JV, ITAT reversed AO's decision, holding that expenses were legitimate business expenditures deductible under section 37. Since AO had accepted these as revenue expenditure rather than capital expenditure, technical service fees were allowed as claimed. Revenue's appeals dismissed.
Taxpayer denied deduction under section 80IA as they failed to meet statutory requirements for infrastructure development projects. ITAT found that LMRCL, being a special purpose vehicle with 50:50 equity between Central and State governments, did not qualify as government authority/statutory body under section 80IA(4). Assessee's role was limited to tunnel construction per contract specifications. Regarding disallowance of technical service fees paid to Gulemark TPL JV, ITAT reversed AO's decision, holding that expenses were legitimate business expenditures deductible under section 37. Since AO had accepted these as revenue expenditure rather than capital expenditure, technical service fees were allowed as claimed. Revenue's appeals dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902