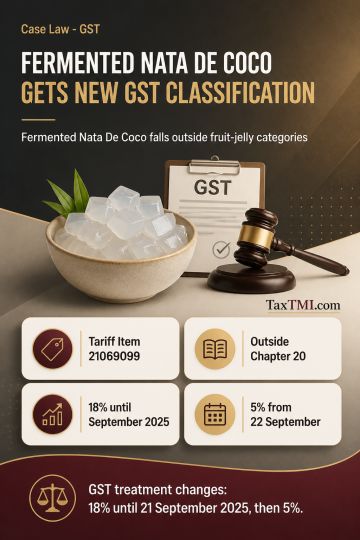
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
CESTAT upheld rejection of a customs duty refund claim filed on 09.01.2024 relating to payments made via challans between March-December 2017 under EPCG scheme. The appellant's claim was time-barred under Section 27 of Customs Act, 1962, as it exceeded the one-year limitation period from duty payment date. The Tribunal noted that no statutory relaxations under Section 27(1B) were applicable. Following precedent from IFGL Refractories case, CESTAT found no grounds to interfere with the original order rejecting the refund claim due to clear statutory time-bar. The appeal was dismissed on merits, affirming that limitation periods under Customs Act must be strictly observed.
CESTAT upheld rejection of a customs duty refund claim filed on 09.01.2024 relating to payments made via challans between March-December 2017 under EPCG scheme. The appellant's claim was time-barred under Section 27 of Customs Act, 1962, as it exceeded the one-year limitation period from duty payment date. The Tribunal noted that no statutory relaxations under Section 27(1B) were applicable. Following precedent from IFGL Refractories case, CESTAT found no grounds to interfere with the original order rejecting the refund claim due to clear statutory time-bar. The appeal was dismissed on merits, affirming that limitation periods under Customs Act must be strictly observed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899