Scientific research institution approval is conditional on SIRO recognition, annual donation reporting, donor certification, and prescribed compliance...
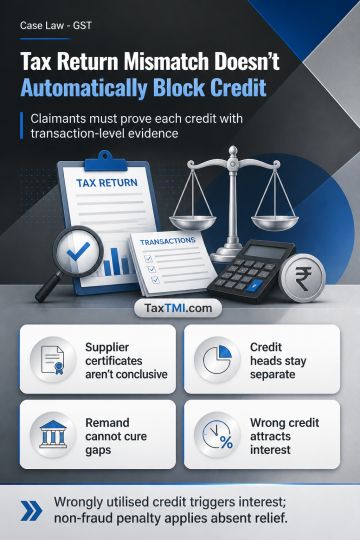
The HC held that transitional Cenvat Credit carried forward qualifies as "input tax credit" under the CGST Act. Interest u/s 50(3) is payable for wrongly availing and utilizing such credit. However, imposing penalty u/s 122(2)(b) read with 74(1) requires evidence of fraud or willful misstatement, which was absent as the petitioner acted under a bona fide belief. While upholding interest liability, the HC quashed the penalty recognizing lack of fraudulent intent by the petitioner, a government company. The petition was allowed in part.
The HC held that transitional Cenvat Credit carried forward qualifies as "input tax credit" under the CGST Act. Interest u/s 50(3) is payable for wrongly availing and utilizing such credit. However, imposing penalty u/s 122(2)(b) read with 74(1) requires evidence of fraud or willful misstatement, which was absent as the petitioner acted under a bona fide belief. While upholding interest liability, the HC quashed the penalty recognizing lack of fraudulent intent by the petitioner, a government company. The petition was allowed in part.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888