Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
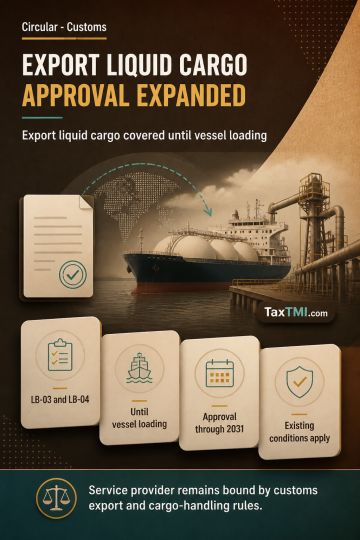
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
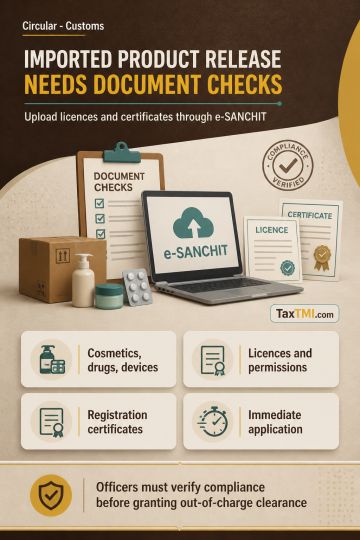
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
Page of 4931
Press 'Enter' after typing page number.
201 to 220 of 98613 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
The High Court held that the Summary of Show Cause Notice along with the attachment containing tax determination cannot substitute a proper Show Cause Notice as mandated u/s 73 of the CGST/SGST Acts. The impugned order was quashed as it violated principles of natural justice by not providing an opportunity of hearing u/s 75(4) before passing the order. The Court clarified that the Statement u/s 73(3) cannot be treated as a Show Cause Notice required u/s 73(1). Further, Rule 26(3) mandates authentication of the Show Cause Notice, Statement, and Order, which was not followed. Consequently, the impugned order was set aside and the petition disposed of on technical grounds of non-issuance of a proper Show Cause Notice and violation of statutory provisions.
The High Court held that the Summary of Show Cause Notice along with the attachment containing tax determination cannot substitute a proper Show Cause Notice as mandated u/s 73 of the CGST/SGST Acts. The impugned order was quashed as it violated principles of natural justice by not providing an opportunity of hearing u/s 75(4) before passing the order. The Court clarified that the Statement u/s 73(3) cannot be treated as a Show Cause Notice required u/s 73(1). Further, Rule 26(3) mandates authentication of the Show Cause Notice, Statement, and Order, which was not followed. Consequently, the impugned order was set aside and the petition disposed of on technical grounds of non-issuance of a proper Show Cause Notice and violation of statutory provisions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931