Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
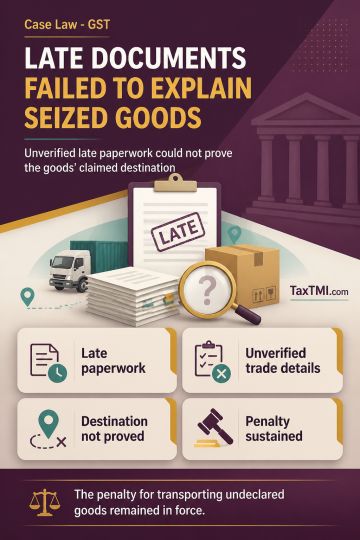
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
The High Court dismissed the challenge to the assessment order regarding wrongful availing of input tax credit. The court found the petitioner's claim of surrendering registration under TNVAT Act and CST Act on 25.12.2014 implausible, as it was a holiday and an acknowledgment would not have been issued on that date. The court directed the respondents to verify from which IP address the transactions were made for filing returns in the petitioner's name during the disputed period, facilitating wrongful availing of input tax credit and passing it to unscrupulous dealers.
The High Court dismissed the challenge to the assessment order regarding wrongful availing of input tax credit. The court found the petitioner's claim of surrendering registration under TNVAT Act and CST Act on 25.12.2014 implausible, as it was a holiday and an acknowledgment would not have been issued on that date. The court directed the respondents to verify from which IP address the transactions were made for filing returns in the petitioner's name during the disputed period, facilitating wrongful availing of input tax credit and passing it to unscrupulous dealers.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929