Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
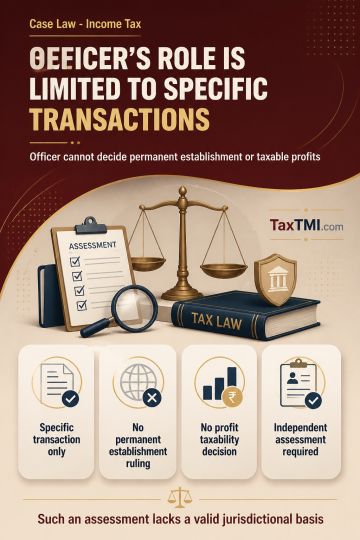
Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
The Assessing Officer (AO) erred in considering the agreed rent as per the agreement instead of the actual rent received from M/s. Mobivil Technologies India Pvt. Ltd. of Rs. 3,74,879/- and TDS deducted thereon of Rs. 37,492/-. The addition made by the AO on the difference between the actual rent received and agreed rent was unjustified. The assessee raised bills under "office rent" and paid CGST & SGST on the monthly rent received. Therefore, the addition made by the AO and confirmed by the CIT(A) was deleted.
The Assessing Officer (AO) erred in considering the agreed rent as per the agreement instead of the actual rent received from M/s. Mobivil Technologies India Pvt. Ltd. of Rs. 3,74,879/- and TDS deducted thereon of Rs. 37,492/-. The addition made by the AO on the difference between the actual rent received and agreed rent was unjustified. The assessee raised bills under "office rent" and paid CGST & SGST on the monthly rent received. Therefore, the addition made by the AO and confirmed by the CIT(A) was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908