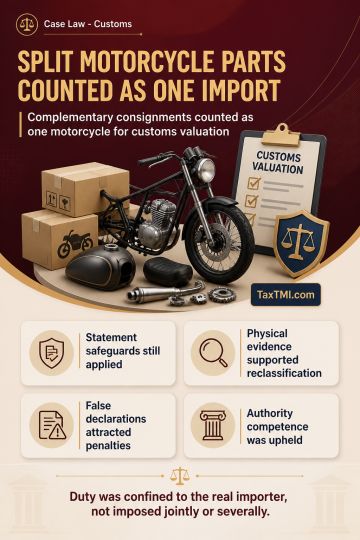
Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Deposits made by assessee in Krishi Bank were fixed deposit investments, not trading activity. Loss suffered when bank went into liquidation is capital loss, not business loss u/s 28 or bad debt u/s 36(1)(vii). Assessing Officer and appellate authorities rightly treated loss as capital loss based on evidence. No substantial question of law arises for adjudication u/s 260A as it involves findings of fact which cannot be re-adjudicated in appeal. Substantial question of law answered against assessee in favor of revenue.
Deposits made by assessee in Krishi Bank were fixed deposit investments, not trading activity. Loss suffered when bank went into liquidation is capital loss, not business loss u/s 28 or bad debt u/s 36(1)(vii). Assessing Officer and appellate authorities rightly treated loss as capital loss based on evidence. No substantial question of law arises for adjudication u/s 260A as it involves findings of fact which cannot be re-adjudicated in appeal. Substantial question of law answered against assessee in favor of revenue.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925