Transfer-pricing treatment of ITeS margins excludes pass-through tax recoveries and separate delayed-receivables interest after working-capital adjust...
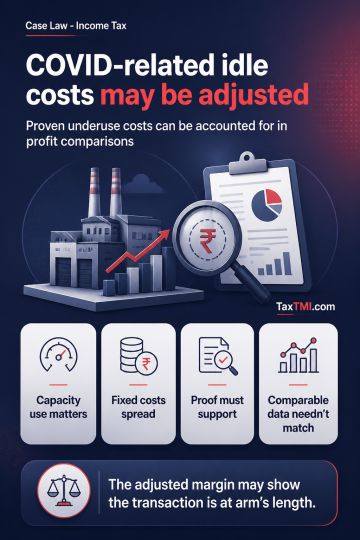
Capacity-utilisation adjustments under TNMM can neutralise substantiated COVID-related idle costs where underutilisation materially affects profitabil...
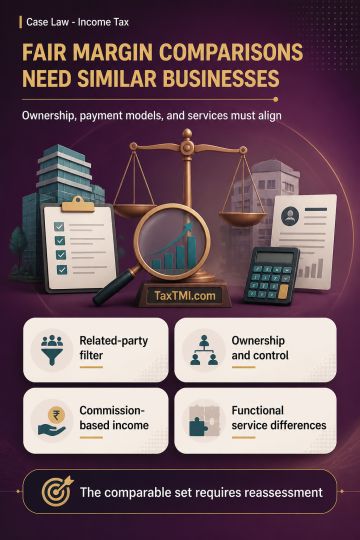
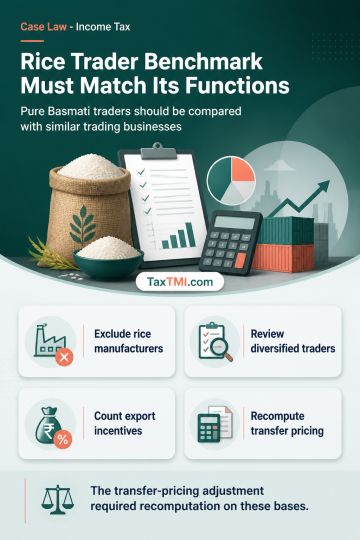
TNMM functional comparability requires excluding rice manufacturers from a pure Basmati rice trader's benchmark and recognising operating export recei...
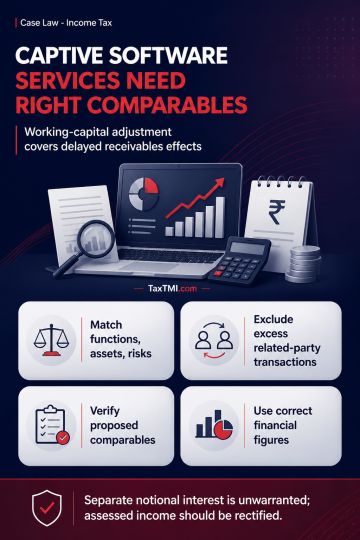
Working-capital adjustment subsumes delayed-receivable effects in TNMM benchmarking of captive software-development services, avoiding separate notion...
Page of 4915
Press 'Enter' after typing page number.
1901 to 1920 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
This is a summary of an order from the Income Tax Appellate Tribunal (ITAT) covering various issues related to the allowability of deductions and expenses claimed by the assessee company. The key points are: Disallowance of deduction u/ss 80IB/80IE for interest on staff advances and statutory/bank deposits was upheld based on coordinate bench rulings. Expenditure for doctors' accommodation and business promotion was disallowed, but the assessee was allowed higher deduction u/ss 80IB/80IE on such disallowance as per CBDT Circular. Disallowance u/s 14A read with Rule 8D was set aside for re-computation based on availability of interest-free funds. Disallowance u/r 8D(2)(iii) was remanded back for re-verification. No adjustment was required to book profits u/s 115JB for amortization of intangibles recorded at fair value pursuant to a scheme of arrangement, following coordinate bench rulings. Stamp duty charges incurred for increasing authorized capital pursuant to a court-sanctioned scheme were disallowed as capital expenditure based on Supreme Court judgments. Delayed payment of employees' contribution to ESIC was disallowed u/s 36(1)(va) read with Section 2(24)(x.
This is a summary of an order from the Income Tax Appellate Tribunal (ITAT) covering various issues related to the allowability of deductions and expenses claimed by the assessee company. The key points are: Disallowance of deduction u/ss 80IB/80IE for interest on staff advances and statutory/bank deposits was upheld based on coordinate bench rulings. Expenditure for doctors' accommodation and business promotion was disallowed, but the assessee was allowed higher deduction u/ss 80IB/80IE on such disallowance as per CBDT Circular. Disallowance u/s 14A read with Rule 8D was set aside for re-computation based on availability of interest-free funds. Disallowance u/r 8D(2)(iii) was remanded back for re-verification. No adjustment was required to book profits u/s 115JB for amortization of intangibles recorded at fair value pursuant to a scheme of arrangement, following coordinate bench rulings. Stamp duty charges incurred for increasing authorized capital pursuant to a court-sanctioned scheme were disallowed as capital expenditure based on Supreme Court judgments. Delayed payment of employees' contribution to ESIC was disallowed u/s 36(1)(va) read with Section 2(24)(x.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915