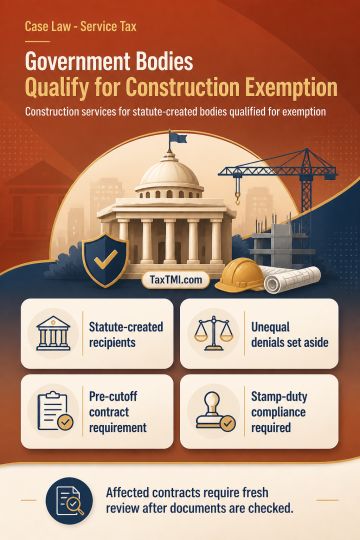
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
This is a summary of an order from the Income Tax Appellate Tribunal (ITAT) covering various issues related to the allowability of deductions and expenses claimed by the assessee company. The key points are: Disallowance of deduction u/ss 80IB/80IE for interest on staff advances and statutory/bank deposits was upheld based on coordinate bench rulings. Expenditure for doctors' accommodation and business promotion was disallowed, but the assessee was allowed higher deduction u/ss 80IB/80IE on such disallowance as per CBDT Circular. Disallowance u/s 14A read with Rule 8D was set aside for re-computation based on availability of interest-free funds. Disallowance u/r 8D(2)(iii) was remanded back for re-verification. No adjustment was required to book profits u/s 115JB for amortization of intangibles recorded at fair value pursuant to a scheme of arrangement, following coordinate bench rulings. Stamp duty charges incurred for increasing authorized capital pursuant to a court-sanctioned scheme were disallowed as capital expenditure based on Supreme Court judgments. Delayed payment of employees' contribution to ESIC was disallowed u/s 36(1)(va) read with Section 2(24)(x.
This is a summary of an order from the Income Tax Appellate Tribunal (ITAT) covering various issues related to the allowability of deductions and expenses claimed by the assessee company. The key points are: Disallowance of deduction u/ss 80IB/80IE for interest on staff advances and statutory/bank deposits was upheld based on coordinate bench rulings. Expenditure for doctors' accommodation and business promotion was disallowed, but the assessee was allowed higher deduction u/ss 80IB/80IE on such disallowance as per CBDT Circular. Disallowance u/s 14A read with Rule 8D was set aside for re-computation based on availability of interest-free funds. Disallowance u/r 8D(2)(iii) was remanded back for re-verification. No adjustment was required to book profits u/s 115JB for amortization of intangibles recorded at fair value pursuant to a scheme of arrangement, following coordinate bench rulings. Stamp duty charges incurred for increasing authorized capital pursuant to a court-sanctioned scheme were disallowed as capital expenditure based on Supreme Court judgments. Delayed payment of employees' contribution to ESIC was disallowed u/s 36(1)(va) read with Section 2(24)(x.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915