Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
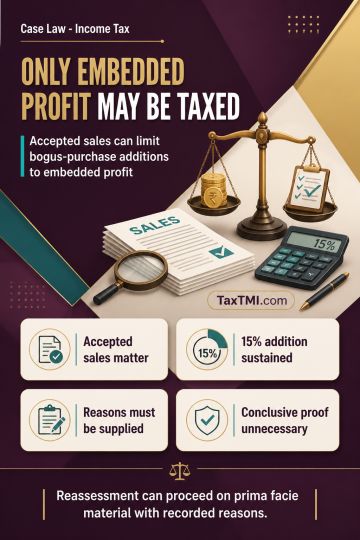
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Determination of tax liability and treatment as Association of Persons (AOP) for assessee trusts. Examination required on whether income taxable at slab rates u/s 164(1) or as AOP u/s 167B at Maximum Marginal Rate. Rectification application pending u/s 154. Issue restored to Assessing Officer for fresh consideration after examining all relevant details and documents. Appeals allowed for statistical purposes. Jurisdictional Assessing Officer to examine and verify necessary details for determining appropriate tax treatment.
Determination of tax liability and treatment as Association of Persons (AOP) for assessee trusts. Examination required on whether income taxable at slab rates u/s 164(1) or as AOP u/s 167B at Maximum Marginal Rate. Rectification application pending u/s 154. Issue restored to Assessing Officer for fresh consideration after examining all relevant details and documents. Appeals allowed for statistical purposes. Jurisdictional Assessing Officer to examine and verify necessary details for determining appropriate tax treatment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915