Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
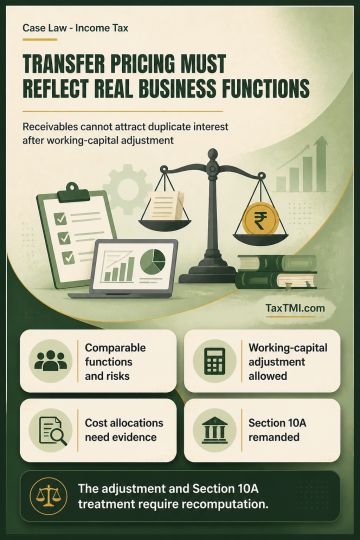
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Determination of tax liability and treatment as Association of Persons (AOP) for assessee trusts. Examination required on whether income taxable at slab rates u/s 164(1) or as AOP u/s 167B at Maximum Marginal Rate. Rectification application pending u/s 154. Issue restored to Assessing Officer for fresh consideration after examining all relevant details and documents. Appeals allowed for statistical purposes. Jurisdictional Assessing Officer to examine and verify necessary details for determining appropriate tax treatment.
Determination of tax liability and treatment as Association of Persons (AOP) for assessee trusts. Examination required on whether income taxable at slab rates u/s 164(1) or as AOP u/s 167B at Maximum Marginal Rate. Rectification application pending u/s 154. Issue restored to Assessing Officer for fresh consideration after examining all relevant details and documents. Appeals allowed for statistical purposes. Jurisdictional Assessing Officer to examine and verify necessary details for determining appropriate tax treatment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915