Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Way Leave Permissions cannot be retrospectively revived through insolvency plans, and affected infrastructure holders require safety review and hearin...
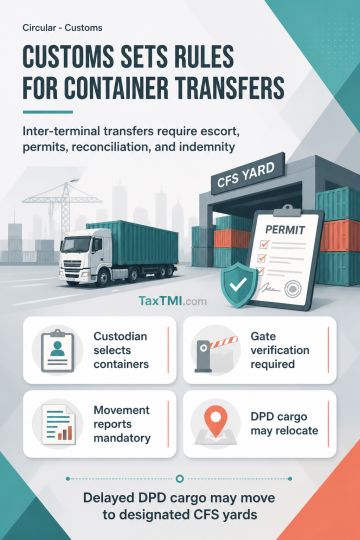
Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
Appellant booked artificial short-term capital loss by purchasing shares from group entities at exorbitant rates and selling same shares to other group entities at lower rates to offset huge capital gains. Transaction lacked genuineness, designed solely to avoid taxes. Cost of purchase rightly recomputed by authorities at Rs.33 per share. Interest expenditure disallowed u/s 14A as appellant failed to substantiate investments were for strategic business purposes, admitted using interest-bearing funds for non-business investments yielding exempt income. CIT(A)'s order upheld, assessee's appeal dismissed by Appellate Tribunal.
Appellant booked artificial short-term capital loss by purchasing shares from group entities at exorbitant rates and selling same shares to other group entities at lower rates to offset huge capital gains. Transaction lacked genuineness, designed solely to avoid taxes. Cost of purchase rightly recomputed by authorities at Rs.33 per share. Interest expenditure disallowed u/s 14A as appellant failed to substantiate investments were for strategic business purposes, admitted using interest-bearing funds for non-business investments yielding exempt income. CIT(A)'s order upheld, assessee's appeal dismissed by Appellate Tribunal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910