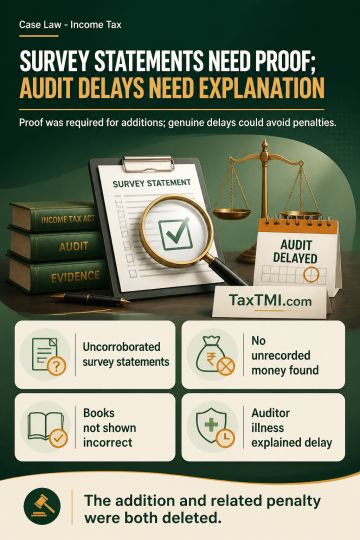
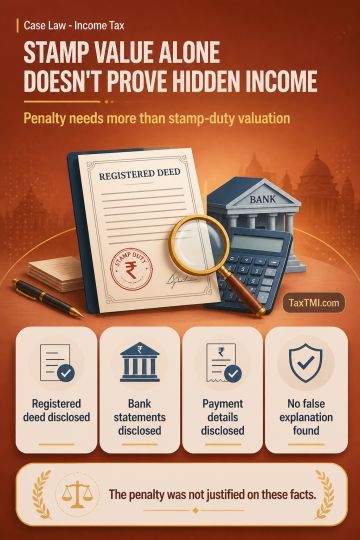
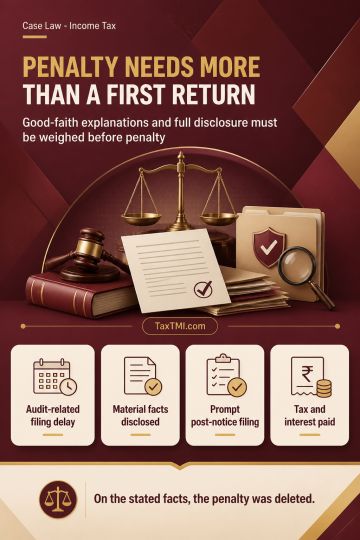
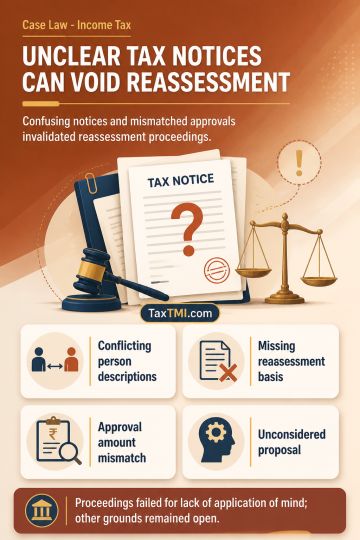
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
The key points are: Appropriation of Rs. 11,00,000 deposited under protest during investigation cannot be considered as acceptance of liability. The extended period of limitation u/s 73(1) of the Finance Act cannot be invoked as the department failed to substantiate that the appellant suppressed material facts with an intent to evade service tax payment. The Supreme Court and Delhi High Court have held that for invoking extended limitation, suppression of facts must be willful with intent to evade tax. The burden of proving willful suppression lies on the department. Mere non-payment or short payment does not constitute suppression unless there is a deliberate act to evade tax with intent. The Tribunal dismissed the department's appeal against the Commissioner's order holding that extended limitation cannot be invoked in this case.
The key points are: Appropriation of Rs. 11,00,000 deposited under protest during investigation cannot be considered as acceptance of liability. The extended period of limitation u/s 73(1) of the Finance Act cannot be invoked as the department failed to substantiate that the appellant suppressed material facts with an intent to evade service tax payment. The Supreme Court and Delhi High Court have held that for invoking extended limitation, suppression of facts must be willful with intent to evade tax. The burden of proving willful suppression lies on the department. Mere non-payment or short payment does not constitute suppression unless there is a deliberate act to evade tax with intent. The Tribunal dismissed the department's appeal against the Commissioner's order holding that extended limitation cannot be invoked in this case.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4865