Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
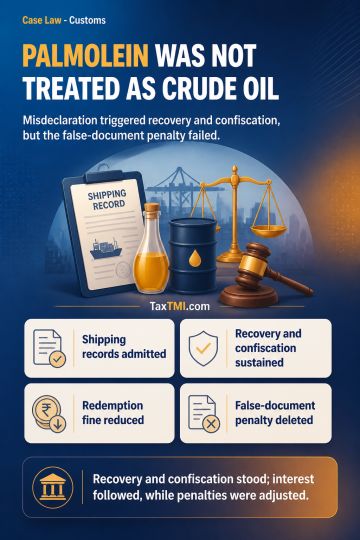
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
Bed sheets imported were correctly classified under CTH 6304 as bed spreads/bed sheets, despite being made of 100% polyester yarn. Although woven fabric of synthetic filament yarn, their identity as bed spreads/bed sheets remained intact, making them classifiable under CTH 6304. Respondents liable to pay duty by classifying goods under CTH 6304, but not liable for confiscation or penalties u/s 114A of Customs Act, 1962. No redemption fine payable. Appeals filed by Revenue dismissed.
Bed sheets imported were correctly classified under CTH 6304 as bed spreads/bed sheets, despite being made of 100% polyester yarn. Although woven fabric of synthetic filament yarn, their identity as bed spreads/bed sheets remained intact, making them classifiable under CTH 6304. Respondents liable to pay duty by classifying goods under CTH 6304, but not liable for confiscation or penalties u/s 114A of Customs Act, 1962. No redemption fine payable. Appeals filed by Revenue dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927