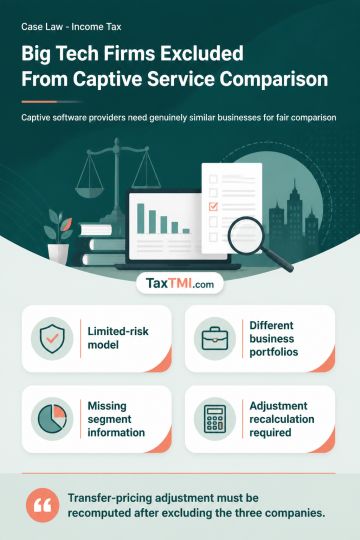
Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
Separate corporate personality prevents directors from being personally liable for company deposits without a guarantee or independent legal undertaki...
Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
The petitioner's obligation under the contract was to source non-standard goods, as per KINFRA's designs and specifications, from vendors outside the state for incorporation in the works contract in Kerala. Even though the goods initially entered Kerala before being incorporated, breaking the chain of movement, this did not alter the inter-state nature of the transaction as the goods were specifically sourced from outside for the contract. The mere intervening event of the goods entering Kerala could not render it an intra-state sale. Therefore, the petitioner was not liable to pay tax under the KGST Act on the inter-state supply of goods for the works contract execution in Kerala. The High Court allowed the revisions, setting aside the Appellate Tribunal's orders and answering the questions of law in favor of the assessee against the revenue.
The petitioner's obligation under the contract was to source non-standard goods, as per KINFRA's designs and specifications, from vendors outside the state for incorporation in the works contract in Kerala. Even though the goods initially entered Kerala before being incorporated, breaking the chain of movement, this did not alter the inter-state nature of the transaction as the goods were specifically sourced from outside for the contract. The mere intervening event of the goods entering Kerala could not render it an intra-state sale. Therefore, the petitioner was not liable to pay tax under the KGST Act on the inter-state supply of goods for the works contract execution in Kerala. The High Court allowed the revisions, setting aside the Appellate Tribunal's orders and answering the questions of law in favor of the assessee against the revenue.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927