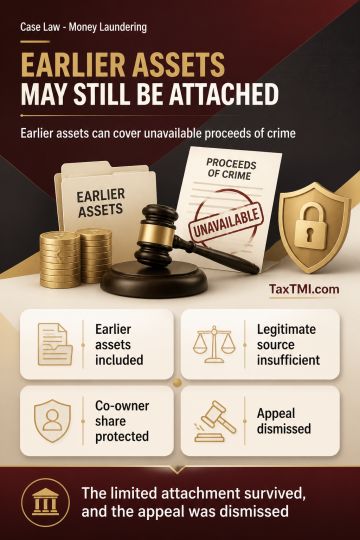
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
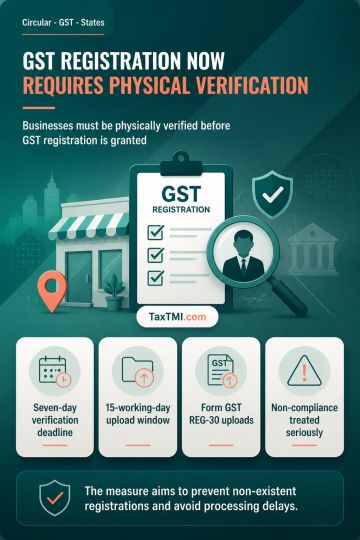
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
The case involved a dispute over the determination of agricultural income, focusing on the variance between admitted and net agricultural income. The Assessing Officer (AO) added an amount u/s 69 due to the difference in agricultural income reported. The case underwent limited scrutiny to verify the income source. The Appellate Tribunal noted that the assessee had submitted a sworn affidavit asserting the sole source of agricultural activity without investing the disputed amount. The AO did not challenge this affidavit, and the assessee was not cross-examined. Citing legal precedents, the Tribunal ruled in favor of the assessee, emphasizing that sworn statements should be accepted unless proven otherwise. Consequently, the AO's addition to the assessee's income was overturned.
The case involved a dispute over the determination of agricultural income, focusing on the variance between admitted and net agricultural income. The Assessing Officer (AO) added an amount u/s 69 due to the difference in agricultural income reported. The case underwent limited scrutiny to verify the income source. The Appellate Tribunal noted that the assessee had submitted a sworn affidavit asserting the sole source of agricultural activity without investing the disputed amount. The AO did not challenge this affidavit, and the assessee was not cross-examined. Citing legal precedents, the Tribunal ruled in favor of the assessee, emphasizing that sworn statements should be accepted unless proven otherwise. Consequently, the AO's addition to the assessee's income was overturned.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918