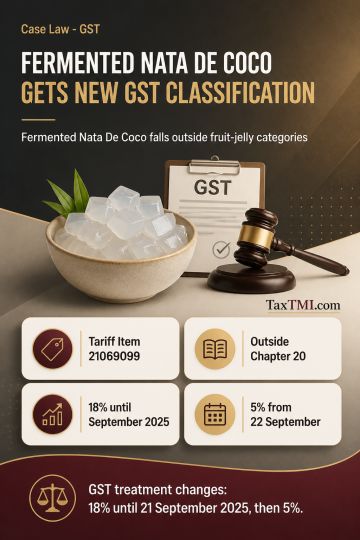
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
The case involved a dispute over the determination of agricultural income, focusing on the variance between admitted and net agricultural income. The Assessing Officer (AO) added an amount u/s 69 due to the difference in agricultural income reported. The case underwent limited scrutiny to verify the income source. The Appellate Tribunal noted that the assessee had submitted a sworn affidavit asserting the sole source of agricultural activity without investing the disputed amount. The AO did not challenge this affidavit, and the assessee was not cross-examined. Citing legal precedents, the Tribunal ruled in favor of the assessee, emphasizing that sworn statements should be accepted unless proven otherwise. Consequently, the AO's addition to the assessee's income was overturned.
The case involved a dispute over the determination of agricultural income, focusing on the variance between admitted and net agricultural income. The Assessing Officer (AO) added an amount u/s 69 due to the difference in agricultural income reported. The case underwent limited scrutiny to verify the income source. The Appellate Tribunal noted that the assessee had submitted a sworn affidavit asserting the sole source of agricultural activity without investing the disputed amount. The AO did not challenge this affidavit, and the assessee was not cross-examined. Citing legal precedents, the Tribunal ruled in favor of the assessee, emphasizing that sworn statements should be accepted unless proven otherwise. Consequently, the AO's addition to the assessee's income was overturned.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899