Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
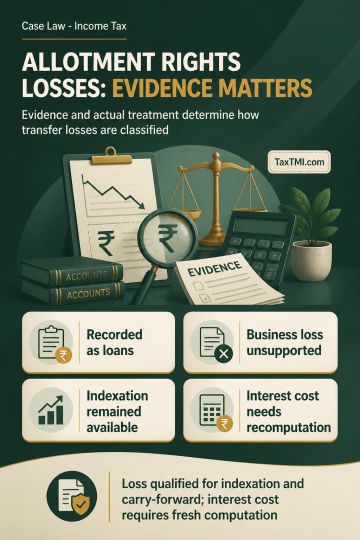
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
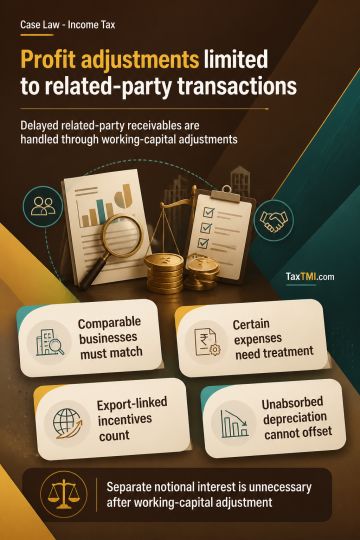
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Page of 4915
Press 'Enter' after typing page number.
1561 to 1580 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
The case involved a dispute regarding the dishonour of cheques, with the key issue being whether the Respondent had a legal obligation to pay back the money under the cheques. The Appellate Court considered the scope of interference in a judgment acquitting the accused and the statutory presumptions u/ss 138 and 139 of the NI Act. The Respondent admitted executing promissory notes and cheques which were later dishonoured. The Court noted that the presumption u/s 139 could be rebutted by the accused with a defense based on a preponderance of probabilities. The Respondent successfully rebutted the presumption by raising doubts about the Petitioner's claims, shifting the burden of proof. The Petitioner failed to discharge this burden, leading to the Respondent's acquittal u/s 138 of the NI Act. The petition seeking leave to appeal was dismissed by the High Court.
The case involved a dispute regarding the dishonour of cheques, with the key issue being whether the Respondent had a legal obligation to pay back the money under the cheques. The Appellate Court considered the scope of interference in a judgment acquitting the accused and the statutory presumptions u/ss 138 and 139 of the NI Act. The Respondent admitted executing promissory notes and cheques which were later dishonoured. The Court noted that the presumption u/s 139 could be rebutted by the accused with a defense based on a preponderance of probabilities. The Respondent successfully rebutted the presumption by raising doubts about the Petitioner's claims, shifting the burden of proof. The Petitioner failed to discharge this burden, leading to the Respondent's acquittal u/s 138 of the NI Act. The petition seeking leave to appeal was dismissed by the High Court.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915