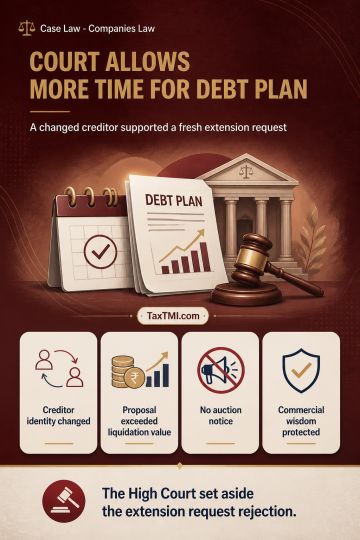
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
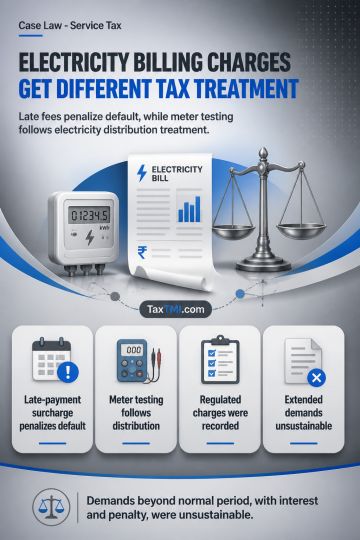
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
The impugned show cause notice (SCN) did not contain any...
GST registration cancellation order & SCN set aside due to vague allegations violating natural justice. Cryptic notice can't be basis for cancellation.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
The impugned show cause notice (SCN) did not contain any specific allegations against the petitioner regarding issuance of invoices without supply of goods, merely referring to Rule 21(g) and stating violation of Rule 86B. The SCN lacked details of invoices allegedly not covered by supply of goods, violating principles of natural justice as the noticee could not respond to vague allegations. The impugned order cancelling GST registration with retrospective effect went beyond the scope of the SCN. The High Court set aside the cancellation order and SCN, directing restoration of the petitioner's GST registration forthwith, as the cryptic allegations could not be the basis for cancellation.
The impugned show cause notice (SCN) did not contain any specific allegations against the petitioner regarding issuance of invoices without supply of goods, merely referring to Rule 21(g) and stating violation of Rule 86B. The SCN lacked details of invoices allegedly not covered by supply of goods, violating principles of natural justice as the noticee could not respond to vague allegations. The impugned order cancelling GST registration with retrospective effect went beyond the scope of the SCN. The High Court set aside the cancellation order and SCN, directing restoration of the petitioner's GST registration forthwith, as the cryptic allegations could not be the basis for cancellation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902