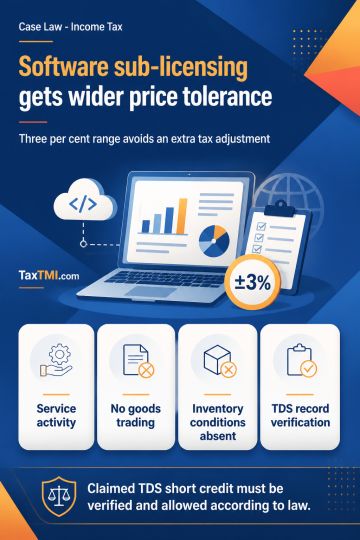
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
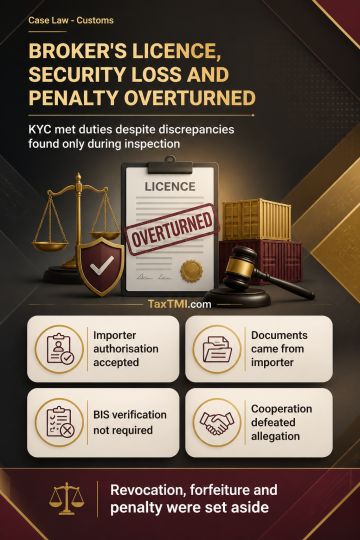
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
The impugned show cause notice (SCN) did not contain any...
GST registration cancellation order & SCN set aside due to vague allegations violating natural justice. Cryptic notice can't be basis for cancellation.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
The impugned show cause notice (SCN) did not contain any specific allegations against the petitioner regarding issuance of invoices without supply of goods, merely referring to Rule 21(g) and stating violation of Rule 86B. The SCN lacked details of invoices allegedly not covered by supply of goods, violating principles of natural justice as the noticee could not respond to vague allegations. The impugned order cancelling GST registration with retrospective effect went beyond the scope of the SCN. The High Court set aside the cancellation order and SCN, directing restoration of the petitioner's GST registration forthwith, as the cryptic allegations could not be the basis for cancellation.
The impugned show cause notice (SCN) did not contain any specific allegations against the petitioner regarding issuance of invoices without supply of goods, merely referring to Rule 21(g) and stating violation of Rule 86B. The SCN lacked details of invoices allegedly not covered by supply of goods, violating principles of natural justice as the noticee could not respond to vague allegations. The impugned order cancelling GST registration with retrospective effect went beyond the scope of the SCN. The High Court set aside the cancellation order and SCN, directing restoration of the petitioner's GST registration forthwith, as the cryptic allegations could not be the basis for cancellation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899