Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Reverse charge applies when registered persons procure specified waste, scrap and used cooking oil from unregistered suppliers.
    Reverse charge on specified waste supplies makes registered recipients liable for IGST on purchases from unregistered suppliers.
    GST exemption for intra-State psyllium seed supplies takes effect under the amended rate schedule from November 2026.
    Absolute IGST exemption now covers inter-State supplies of psyllium seeds under the amended goods exemption schedule.
    UTGST exemption for psyllium seeds takes effect through their inclusion in the absolute exemption schedule.
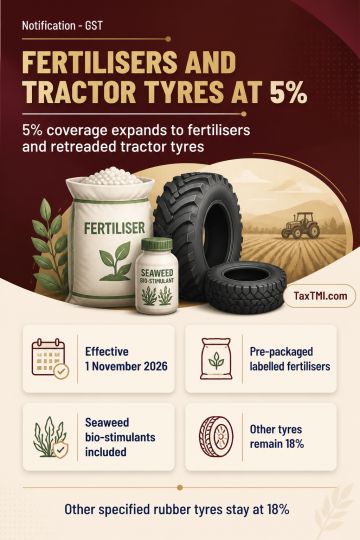
    CGST rate schedules place eligible fertilisers and retreaded tractor tyres in the lower rate schedule.
    IGST rate schedules place fertilisers and retreaded tractor tyres at 5%, while other specified rubber tyres remain at 18%.
    E-commerce warehouse registration enables eligible goods suppliers to register without local physical presence, subject to operator consent and verifi...
    E-invoicing scope expands to reverse-charge purchases and imported services, extending compliance obligations for covered GST taxpayers.
    Water-Stability Test Determines Classification of Low-Ethoxylated Fatty Alcohol Ethoxylates Outside the Organic Surface-Active Agent Category
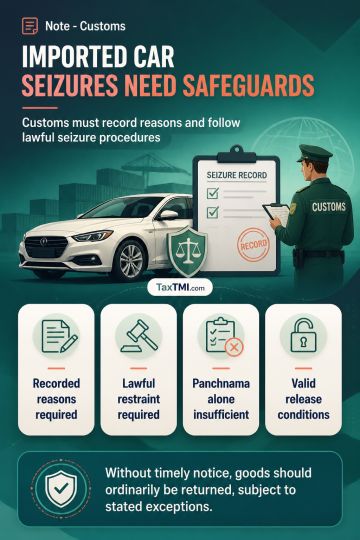
    Imported car seizure safeguards require recorded grounds, lawful restraint, timely notice, and valid provisional release conditions.
    Fraudulent input tax credit demands require proof of fictitious supplies, absent deliveries, and culpable conduct beyond supplier cancellation alone.
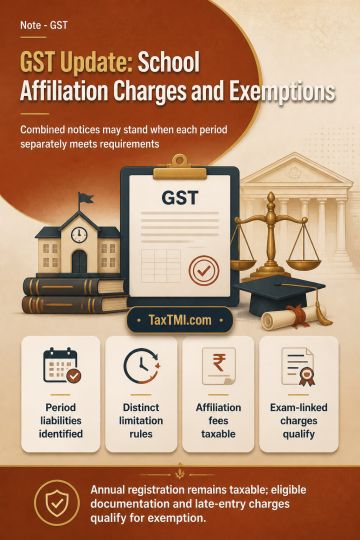
    Consolidated GST notices may remain valid period-wise, while school affiliation fees are taxable independent supplies.
    Corporate veil-piercing in award execution requires evidence of misuse, prompting forensic audit rather than immediate liability.
    Deemed stay on disputed interest recovery applies after full tax payment while appellate proceedings remain pending.
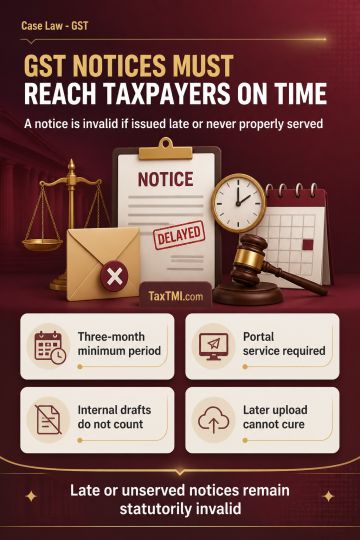
    GST show-cause notice limitation requires timely portal service; internal generation and later upload cannot cure statutory invalidity.
    Condonation of delay requires consideration of a taxpayer's explanation; failure to do so restores the GST appeal for merits.
    Consideration of delay-condonation grounds required before rejecting GST appeals on limitation; merits review follows upon compliance with conditions.
    Pre-trial detention in GST fake-invoice prosecutions cannot continue after investigation absent risks to trial integrity.
    Pre-arrest reasons for arrest must be communicated, and later constitutional rulings generally apply to earlier arrests.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Petitioner granted regular bail as no incriminating evidence...

Bail granted due to lack of evidence. Custody serves no purpose. Pending cases not a ground to reject bail.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST July 31, 2024 Case Laws HC
Petitioner granted regular bail as no incriminating evidence collected against him during investigation. Offences triable by Magistrate's Court, final report already submitted. Keeping petitioner in custody serves no purpose. Pendency of other criminal cases not ground to reject bail as petitioner made out case for bail. Supreme Court held pendency of several criminal cases cannot be basis to refuse bail. Petitioner ordered to be released on furnishing bail/surety bonds to satisfaction of trial court.

Topics

Acts Income Tax