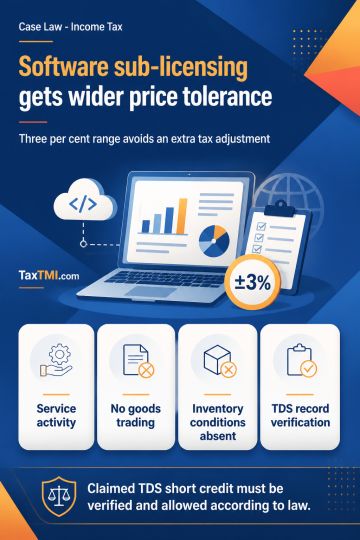
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
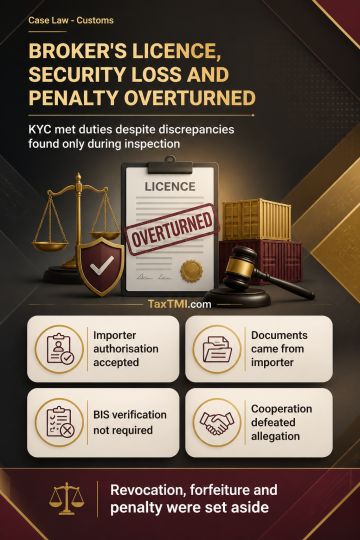
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
Advances given to 5 persons without charging interest were for business purposes. Non-installation of machinery or renovation in subsequent period due to non-viability cannot negate the business purpose. Assessee decided not to proceed with its plan due to bad market condition, which is a valid business decision and consequential expenditure cannot be disallowed. Assessee had sufficient interest-free capital exceeding the interest-free advances, hence disallowance of interest is impermissible as per jurisdictional High Court precedents.
Advances given to 5 persons without charging interest were for business purposes. Non-installation of machinery or renovation in subsequent period due to non-viability cannot negate the business purpose. Assessee decided not to proceed with its plan due to bad market condition, which is a valid business decision and consequential expenditure cannot be disallowed. Assessee had sufficient interest-free capital exceeding the interest-free advances, hence disallowance of interest is impermissible as per jurisdictional High Court precedents.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913