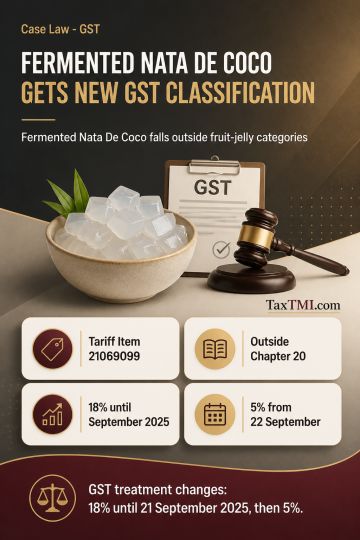
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Transfer pricing adjustment on international transaction involving payment of guarantee fees to associated enterprise was held unjustified. Assessee demonstrated effective borrowing cost including guarantee fee was lower than bank's quoted interest rate, justifying economic rationale. Tax authorities failed to present compelling evidence against guarantee fee. Benefits of lower interest rates and favorable operating margins substantiated arm's length nature. Tribunal had deleted similar addition previously, upheld by High Court considering consistency in operating margin, benefit of lower borrowing costs compared to bank rates justifying guarantee fee. Present case mirrored facts and circumstances, necessitating consistency in judicial decisions for legal certainty and fairness. TP adjustment made by tax authorities was unjustified, addition on account of guarantee fee payment to associated enterprise was deleted.
Transfer pricing adjustment on international transaction involving payment of guarantee fees to associated enterprise was held unjustified. Assessee demonstrated effective borrowing cost including guarantee fee was lower than bank's quoted interest rate, justifying economic rationale. Tax authorities failed to present compelling evidence against guarantee fee. Benefits of lower interest rates and favorable operating margins substantiated arm's length nature. Tribunal had deleted similar addition previously, upheld by High Court considering consistency in operating margin, benefit of lower borrowing costs compared to bank rates justifying guarantee fee. Present case mirrored facts and circumstances, necessitating consistency in judicial decisions for legal certainty and fairness. TP adjustment made by tax authorities was unjustified, addition on account of guarantee fee payment to associated enterprise was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902