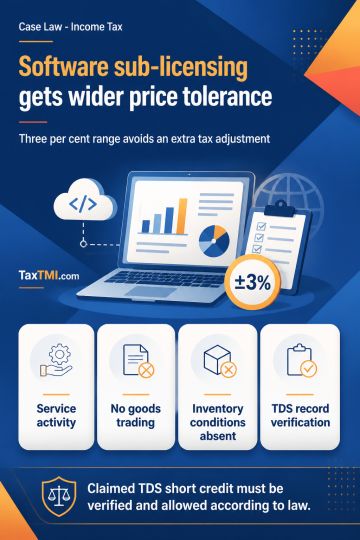
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
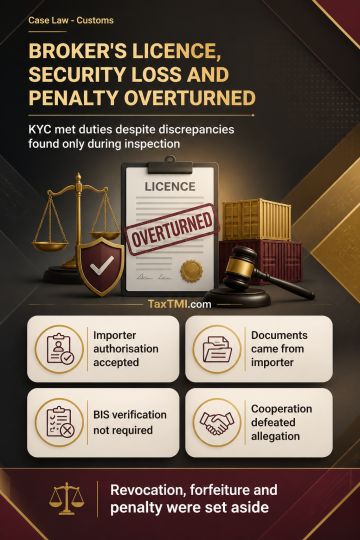
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
Notification seeks to amend Notification No. 02/2018-Integrated Tax, dated 20th September, 2018 regarding rate of tax collection at source (TCS) to be collected by every electronic commerce operator for inter-State taxable supplies and other suppliers where consideration is collected by said operator. The amendment substitutes words "one per cent" with "half per cent" for TCS rate. The notification comes into force from date of publication in official gazette.
Notification seeks to amend Notification No. 02/2018-Integrated Tax, dated 20th September, 2018 regarding rate of tax collection at source (TCS) to be collected by every electronic commerce operator for inter-State taxable supplies and other suppliers where consideration is collected by said operator. The amendment substitutes words "one per cent" with "half per cent" for TCS rate. The notification comes into force from date of publication in official gazette.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899