Factory-consumption condition restricts solar module parts exemption and excludes imported aluminium profiles fabricated outside the production factor...
Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
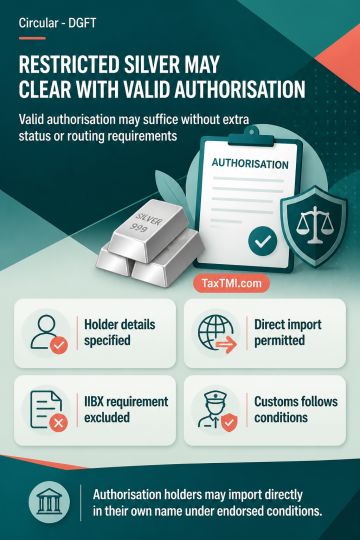
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
The High Court considered a challenge to an assessment order based on disparity between the petitioner's GSTR 3B return and the supplier's GSTR 1 return. The petitioner's explanation for the disparity was noted, attributing it to the supplier's error in reporting turnover. The court found the petitioner negligent for not uploading the reply and not participating in proceedings. The petitioner agreed to remit 10% of the disputed demand for a remand. In the interest of justice, the court quashed the order, allowing the petitioner to contest the tax demand by placing relevant documents on record. The impugned order was set aside on the condition of remitting 10% of the disputed tax demand within two weeks.
The High Court considered a challenge to an assessment order based on disparity between the petitioner's GSTR 3B return and the supplier's GSTR 1 return. The petitioner's explanation for the disparity was noted, attributing it to the supplier's error in reporting turnover. The court found the petitioner negligent for not uploading the reply and not participating in proceedings. The petitioner agreed to remit 10% of the disputed demand for a remand. In the interest of justice, the court quashed the order, allowing the petitioner to contest the tax demand by placing relevant documents on record. The impugned order was set aside on the condition of remitting 10% of the disputed tax demand within two weeks.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929