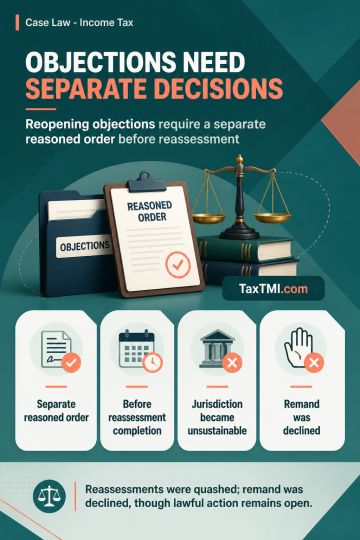
Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
The Appellate Tribunal considered the disallowance of deduction claimed u/s 80-IA due to the assessee's failure to file Form no.10CCB on time. The Tribunal found that the audit report was filed online by the assessee, albeit with a delay. The Tribunal disagreed with the lower authorities' decision, citing that the Supreme Court's ruling in Wipro Ltd. did not support the Revenue's case. The Tribunal noted that the amendment to section 80-IA(7) by the Finance Act, 2020, was not applicable to the assessment year in question. As the audit report was filed within the allowed time, the disallowance of the deduction u/s 80-IA was overturned, and the assessee's appeal was allowed.
The Appellate Tribunal considered the disallowance of deduction claimed u/s 80-IA due to the assessee's failure to file Form no.10CCB on time. The Tribunal found that the audit report was filed online by the assessee, albeit with a delay. The Tribunal disagreed with the lower authorities' decision, citing that the Supreme Court's ruling in Wipro Ltd. did not support the Revenue's case. The Tribunal noted that the amendment to section 80-IA(7) by the Finance Act, 2020, was not applicable to the assessment year in question. As the audit report was filed within the allowed time, the disallowance of the deduction u/s 80-IA was overturned, and the assessee's appeal was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913