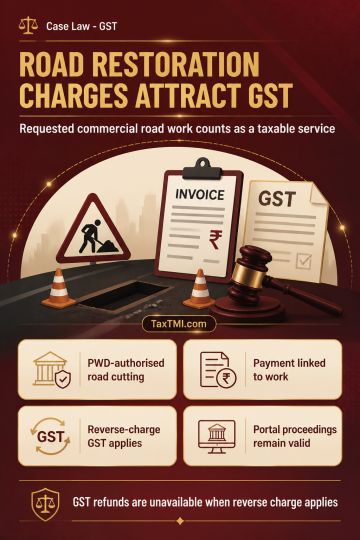
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
The ITAT Amritsar addressed the validity of initiating proceedings u/s 153C(1) instead of 143(3). It was held that initiation of Section 153C occurs upon receiving seized documents by the AO with jurisdiction over the person. The tribunal noted that the initiation u/s 153C(1) was for AY 2021-22, not AY 2020-21, as the documents were handed over on 16-03-2021. Citing precedents like Jasjit Singh and RRJ Securities Ltd, the tribunal deemed the assessment order invalid and quashed it, setting aside the appeal order.
The ITAT Amritsar addressed the validity of initiating proceedings u/s 153C(1) instead of 143(3). It was held that initiation of Section 153C occurs upon receiving seized documents by the AO with jurisdiction over the person. The tribunal noted that the initiation u/s 153C(1) was for AY 2021-22, not AY 2020-21, as the documents were handed over on 16-03-2021. Citing precedents like Jasjit Singh and RRJ Securities Ltd, the tribunal deemed the assessment order invalid and quashed it, setting aside the appeal order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927