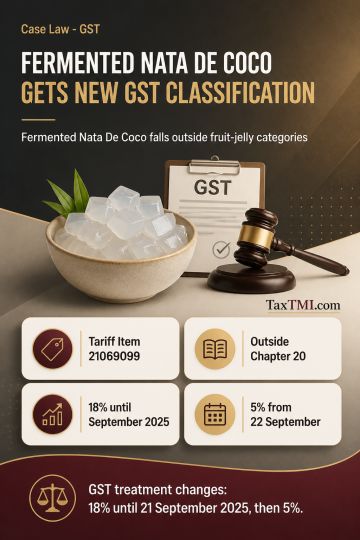
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
The Delhi High Court examined taxability in India of interest received by an Indian Permanent Establishment (PE) from its Head Office/Overseas Branch under the India-US Double Taxation Avoidance Agreement (DTAA). The court referred to the Credit Agricole case, emphasizing that branch offices are not separate legal entities. The court noted that the Explanation to Section 9(1)(v) of the Income Tax Act deals with banking entities, deeming remittances to the Head Office as accruing in India. The court found that the PE of a banking enterprise is not a separate legal entity, rejecting the application of the Explanation introduced in 2016. Referring to the Kikabhai Premchand KT case, the court highlighted the absurdity of a person profiting from itself. The court upheld the view that the branch office cannot profit from itself, and the DTAA provisions for banking enterprises would apply.
The Delhi High Court examined taxability in India of interest received by an Indian Permanent Establishment (PE) from its Head Office/Overseas Branch under the India-US Double Taxation Avoidance Agreement (DTAA). The court referred to the Credit Agricole case, emphasizing that branch offices are not separate legal entities. The court noted that the Explanation to Section 9(1)(v) of the Income Tax Act deals with banking entities, deeming remittances to the Head Office as accruing in India. The court found that the PE of a banking enterprise is not a separate legal entity, rejecting the application of the Explanation introduced in 2016. Referring to the Kikabhai Premchand KT case, the court highlighted the absurdity of a person profiting from itself. The court upheld the view that the branch office cannot profit from itself, and the DTAA provisions for banking enterprises would apply.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899