Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
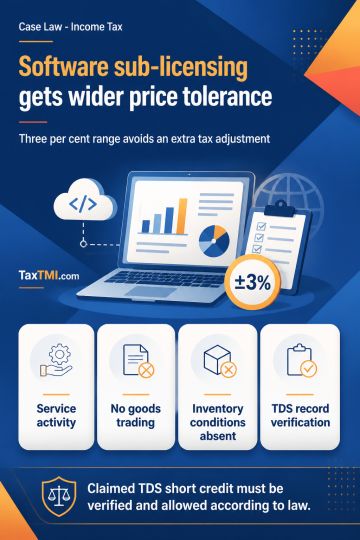
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
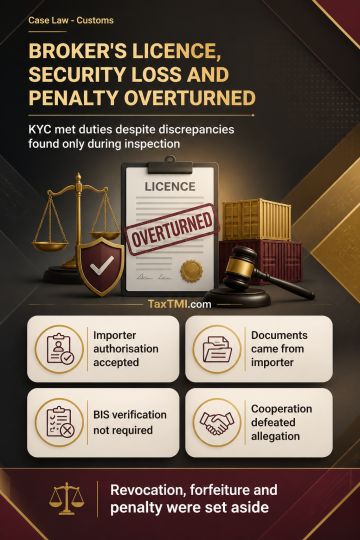
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
The ITAT Ahmedabad considered the eligibility of exemption u/s 11 for an assessee engaged in activities like development planning, town planning schemes, and fee collection. The AO argued the assessee's profit motive disqualifies it from claiming benefits u/s 11 & 12. However, the tribunal referenced the Supreme Court's decision in AUDA case, emphasizing that fees collected for statutory activities are not considered trade or business. Activities like housing development by statutory bodies are not commercial in nature. The nature of the service provided is crucial; essential public services like water or sewage cess are not deemed commercial. Non-statutory bodies engaging in trade promotion or business facilitation may not qualify for charitable status. The tribunal allowed the assessee's appeal based on these principles.
The ITAT Ahmedabad considered the eligibility of exemption u/s 11 for an assessee engaged in activities like development planning, town planning schemes, and fee collection. The AO argued the assessee's profit motive disqualifies it from claiming benefits u/s 11 & 12. However, the tribunal referenced the Supreme Court's decision in AUDA case, emphasizing that fees collected for statutory activities are not considered trade or business. Activities like housing development by statutory bodies are not commercial in nature. The nature of the service provided is crucial; essential public services like water or sewage cess are not deemed commercial. Non-statutory bodies engaging in trade promotion or business facilitation may not qualify for charitable status. The tribunal allowed the assessee's appeal based on these principles.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899