Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
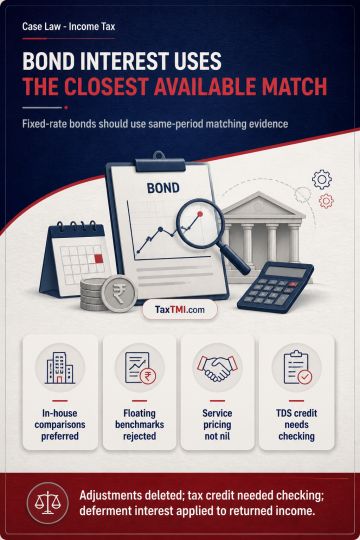
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
CENVAT Credit - input service availed by the appellant at the depot level - The case involved the admissibility of Cenvat Credit on service tax paid for clearing and forwarding services received by the appellant at the depot. The tribunal upheld the appellant's claim, stating that since the ownership of goods remained with them until sold from the depot or consignment agent premises, all input services availed up to that point were eligible for Cenvat Credit. The tribunal interpreted the definition of "place of removal" under the Central Excise Act, 1944, to include the depot of the consignment agent as the place of removal, making services provided up to that point admissible for credit.
CENVAT Credit - input service availed by the appellant at the depot level - The case involved the admissibility of Cenvat Credit on service tax paid for clearing and forwarding services received by the appellant at the depot. The tribunal upheld the appellant's claim, stating that since the ownership of goods remained with them until sold from the depot or consignment agent premises, all input services availed up to that point were eligible for Cenvat Credit. The tribunal interpreted the definition of "place of removal" under the Central Excise Act, 1944, to include the depot of the consignment agent as the place of removal, making services provided up to that point admissible for credit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913