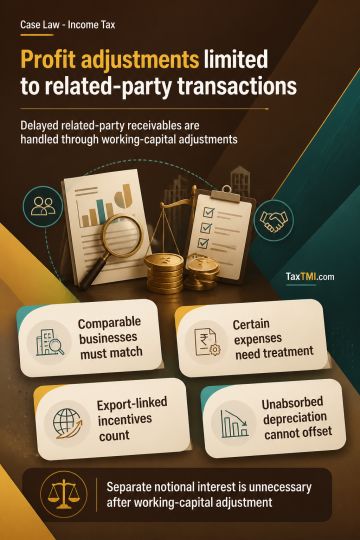
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
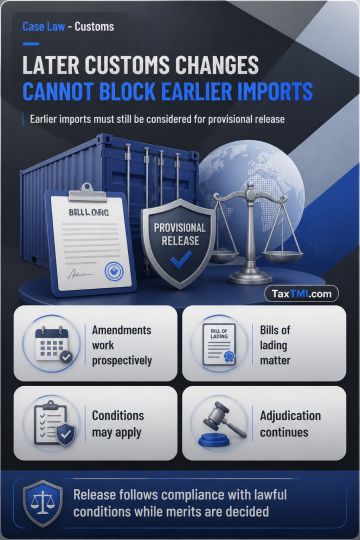
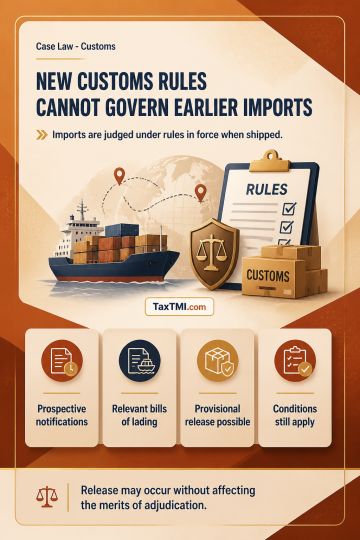
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
Page of 4913
Press 'Enter' after typing page number.
1541 to 1560 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
CENVAT Credit - input service availed by the appellant at the depot level - The case involved the admissibility of Cenvat Credit on service tax paid for clearing and forwarding services received by the appellant at the depot. The tribunal upheld the appellant's claim, stating that since the ownership of goods remained with them until sold from the depot or consignment agent premises, all input services availed up to that point were eligible for Cenvat Credit. The tribunal interpreted the definition of "place of removal" under the Central Excise Act, 1944, to include the depot of the consignment agent as the place of removal, making services provided up to that point admissible for credit.
CENVAT Credit - input service availed by the appellant at the depot level - The case involved the admissibility of Cenvat Credit on service tax paid for clearing and forwarding services received by the appellant at the depot. The tribunal upheld the appellant's claim, stating that since the ownership of goods remained with them until sold from the depot or consignment agent premises, all input services availed up to that point were eligible for Cenvat Credit. The tribunal interpreted the definition of "place of removal" under the Central Excise Act, 1944, to include the depot of the consignment agent as the place of removal, making services provided up to that point admissible for credit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913