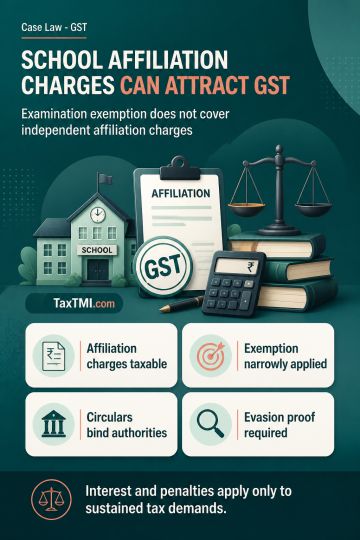
School-affiliation charges remain taxable where not directly connected with examinations, while extended limitation requires proof of deliberate tax e...
Concessional penalty for search-disclosed unreconciled jewellery applies where substantive disclosure conditions are met despite omission from origina...
The notification, issued by the Ministry of Finance, pertains to the modification of the Convention between the Government of India and the Kingdom of Spain for the avoidance of double taxation and prevention of fiscal evasion with respect to taxes on income and on capital. It addresses the taxation of royalties and fees for technical services between the two countries. Specifically, it substitutes paragraph 2 of Article 13 of the Convention, limiting the taxation at source on royalties and fees for technical services to ten per cent of the gross amount, provided the recipient is the beneficial owner.
The notification, issued by the Ministry of Finance, pertains to the modification of the Convention between the Government of India and the Kingdom of Spain for the avoidance of double taxation and prevention of fiscal evasion with respect to taxes on income and on capital. It addresses the taxation of royalties and fees for technical services between the two countries. Specifically, it substitutes paragraph 2 of Article 13 of the Convention, limiting the taxation at source on royalties and fees for technical services to ten per cent of the gross amount, provided the recipient is the beneficial owner.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915