Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
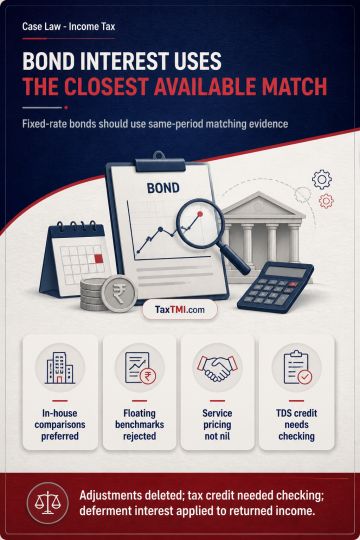
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
The notification, issued by the Ministry of Finance, pertains to the modification of the Convention between the Government of India and the Kingdom of Spain for the avoidance of double taxation and prevention of fiscal evasion with respect to taxes on income and on capital. It addresses the taxation of royalties and fees for technical services between the two countries. Specifically, it substitutes paragraph 2 of Article 13 of the Convention, limiting the taxation at source on royalties and fees for technical services to ten per cent of the gross amount, provided the recipient is the beneficial owner.
The notification, issued by the Ministry of Finance, pertains to the modification of the Convention between the Government of India and the Kingdom of Spain for the avoidance of double taxation and prevention of fiscal evasion with respect to taxes on income and on capital. It addresses the taxation of royalties and fees for technical services between the two countries. Specifically, it substitutes paragraph 2 of Article 13 of the Convention, limiting the taxation at source on royalties and fees for technical services to ten per cent of the gross amount, provided the recipient is the beneficial owner.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913