Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
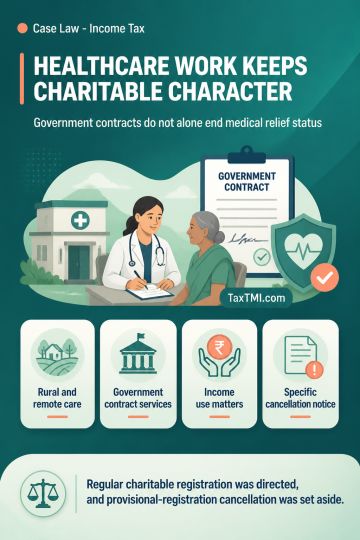
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
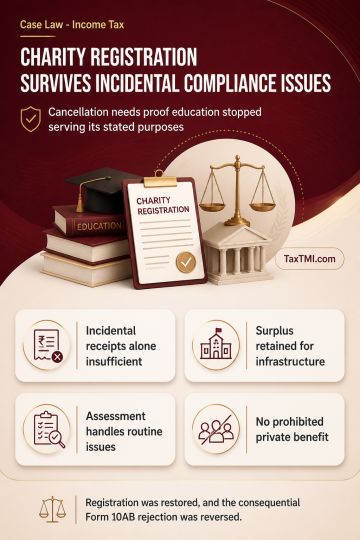
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Page of 4912
Press 'Enter' after typing page number.
1521 to 1540 of 98239 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
The notification, issued by the Ministry of Finance, pertains to the modification of the Convention between the Government of India and the Kingdom of Spain for the avoidance of double taxation and prevention of fiscal evasion with respect to taxes on income and on capital. It addresses the taxation of royalties and fees for technical services between the two countries. Specifically, it substitutes paragraph 2 of Article 13 of the Convention, limiting the taxation at source on royalties and fees for technical services to ten per cent of the gross amount, provided the recipient is the beneficial owner.
The notification, issued by the Ministry of Finance, pertains to the modification of the Convention between the Government of India and the Kingdom of Spain for the avoidance of double taxation and prevention of fiscal evasion with respect to taxes on income and on capital. It addresses the taxation of royalties and fees for technical services between the two countries. Specifically, it substitutes paragraph 2 of Article 13 of the Convention, limiting the taxation at source on royalties and fees for technical services to ten per cent of the gross amount, provided the recipient is the beneficial owner.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912