Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
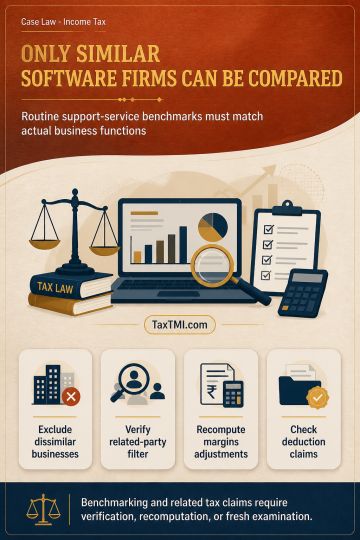
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
The notification, issued by the Ministry of Finance, pertains to the modification of the Convention between the Government of India and the Kingdom of Spain for the avoidance of double taxation and prevention of fiscal evasion with respect to taxes on income and on capital. It addresses the taxation of royalties and fees for technical services between the two countries. Specifically, it substitutes paragraph 2 of Article 13 of the Convention, limiting the taxation at source on royalties and fees for technical services to ten per cent of the gross amount, provided the recipient is the beneficial owner.
The notification, issued by the Ministry of Finance, pertains to the modification of the Convention between the Government of India and the Kingdom of Spain for the avoidance of double taxation and prevention of fiscal evasion with respect to taxes on income and on capital. It addresses the taxation of royalties and fees for technical services between the two countries. Specifically, it substitutes paragraph 2 of Article 13 of the Convention, limiting the taxation at source on royalties and fees for technical services to ten per cent of the gross amount, provided the recipient is the beneficial owner.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918