Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
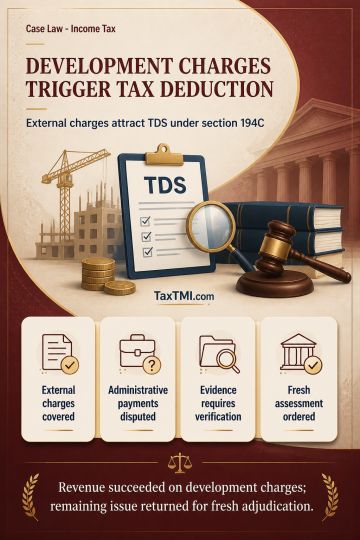
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
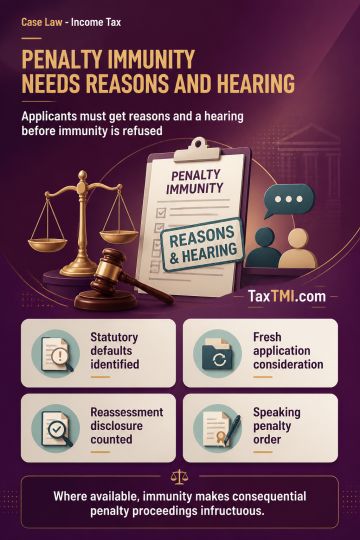
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
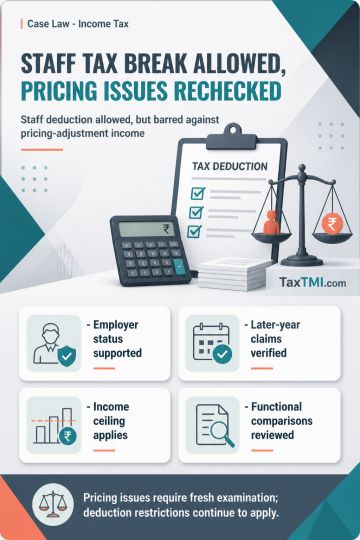
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
Demand Duty - Mis-declaring imported goods ‘Brush Cutters’ as ‘Power Weeders’ - The Tribunal found the goods to be 'Brush Cutters' not 'Power Weeders' based on examination and supporting documentation. They were classified under CTH 8467 as tools for working in the hand with a self-contained motor, distinguishing them from machinery meant for soil preparation or cultivation under CTH 8432/8433. The appellants were not entitled to the claimed exemptions under Notification No.12/2012 because those exemptions applied specifically to machinery designed for agricultural use, which did not include 'Brush Cutters'.
Demand Duty - Mis-declaring imported goods ‘Brush Cutters’ as ‘Power Weeders’ - The Tribunal found the goods to be 'Brush Cutters' not 'Power Weeders' based on examination and supporting documentation. They were classified under CTH 8467 as tools for working in the hand with a self-contained motor, distinguishing them from machinery meant for soil preparation or cultivation under CTH 8432/8433. The appellants were not entitled to the claimed exemptions under Notification No.12/2012 because those exemptions applied specifically to machinery designed for agricultural use, which did not include 'Brush Cutters'.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918