Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
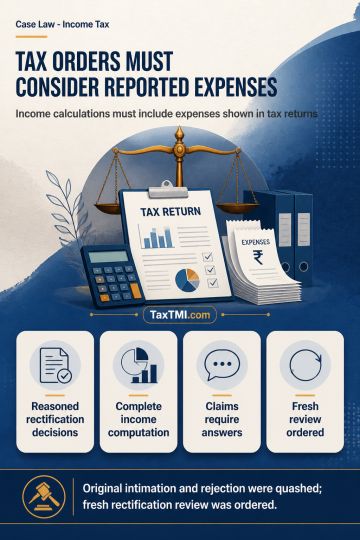
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
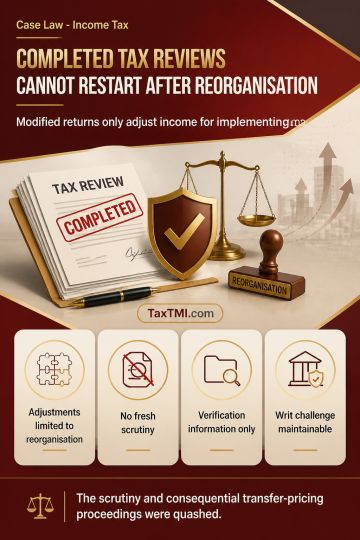
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Disallowance of exemption claimed u/s 54EC - non filling ROI - investment made in REC - assessee has neither filed return of income u/s 139(1) of the Act, nor in response to the notice issued u/s 148 - The tribunal concluded that for claiming exemption under section 54EC of the Income Tax Act, it is not mandatory to file a return of income. - Even at the time of hearing the Ld. DR has not brought our attention to such provision of the Act, suggesting that it is mandatory, for claiming exemption u/s 54EC of the Act, to file the return of income. - AO directed to allow the benefit of exemption.
Disallowance of exemption claimed u/s 54EC - non filling ROI - investment made in REC - assessee has neither filed return of income u/s 139(1) of the Act, nor in response to the notice issued u/s 148 - The tribunal concluded that for claiming exemption under section 54EC of the Income Tax Act, it is not mandatory to file a return of income. - Even at the time of hearing the Ld. DR has not brought our attention to such provision of the Act, suggesting that it is mandatory, for claiming exemption u/s 54EC of the Act, to file the return of income. - AO directed to allow the benefit of exemption.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888