Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
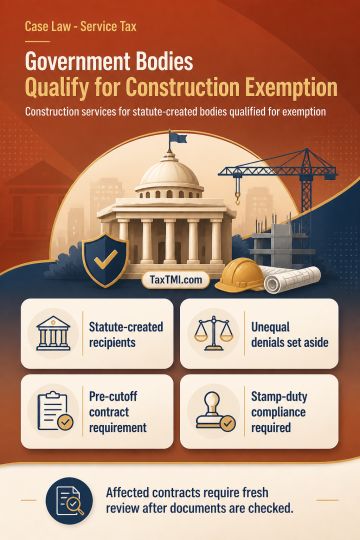
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
Page of 4916
Press 'Enter' after typing page number.
1881 to 1900 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Demand of GST u/s 74 - Wrongful / excess claim of transitional credit (Tran-1) - Though the appellant has claimed state tax as transitional input tax credit, but there is no record of local purchase of taxable commodities during the tax period 2016-17 and 2017-18, nor any reflection of tax credit carried forward in the returns submitted by the appellant for the tax period 2016-17 and 2017-18. - it was a clear willful misstatement on the part of the petitioner - Petition dismissed - HC
Demand of GST u/s 74 - Wrongful / excess claim of transitional credit (Tran-1) - Though the appellant has claimed state tax as transitional input tax credit, but there is no record of local purchase of taxable commodities during the tax period 2016-17 and 2017-18, nor any reflection of tax credit carried forward in the returns submitted by the appellant for the tax period 2016-17 and 2017-18. - it was a clear willful misstatement on the part of the petitioner - Petition dismissed - HC
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916