Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
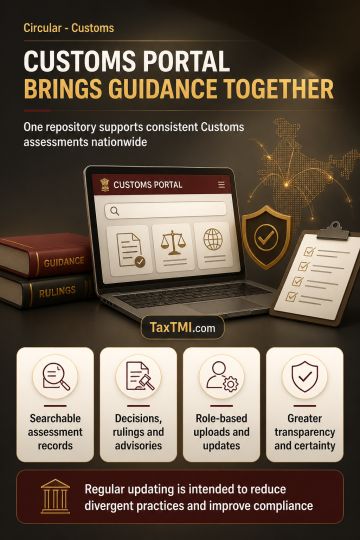
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Page of 4913
Press 'Enter' after typing page number.
1641 to 1660 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Demand of GST u/s 74 - Wrongful / excess claim of transitional credit (Tran-1) - Though the appellant has claimed state tax as transitional input tax credit, but there is no record of local purchase of taxable commodities during the tax period 2016-17 and 2017-18, nor any reflection of tax credit carried forward in the returns submitted by the appellant for the tax period 2016-17 and 2017-18. - it was a clear willful misstatement on the part of the petitioner - Petition dismissed - HC
Demand of GST u/s 74 - Wrongful / excess claim of transitional credit (Tran-1) - Though the appellant has claimed state tax as transitional input tax credit, but there is no record of local purchase of taxable commodities during the tax period 2016-17 and 2017-18, nor any reflection of tax credit carried forward in the returns submitted by the appellant for the tax period 2016-17 and 2017-18. - it was a clear willful misstatement on the part of the petitioner - Petition dismissed - HC
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913