Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
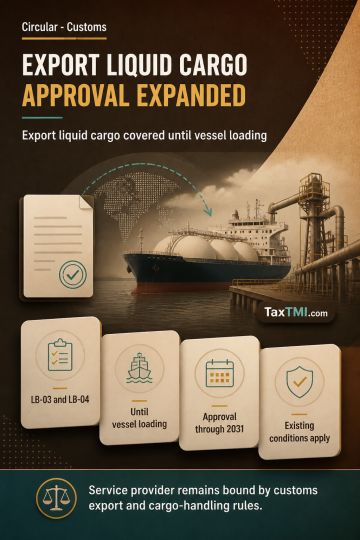
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
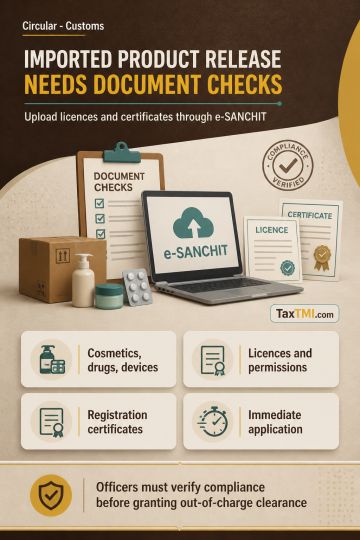
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
Condonation of delay in filing appeal - Or the appeal was filed within the time - Once the appellant had indicated in ST-IV form that the order was received by the appellant only on December 21, 2018, then it was for the Department to have controverted that the order had been received by the appellant earlier to this date and an explanation for the delay should not have been expected from the appellant. - since the appeal has been filed within the period of two months from the date of receipt of order by the appellant, the appeal cannot be dismissed by the commissioner (appeals) on the ground of delay iby calculating the period from the date of order - AT
Condonation of delay in filing appeal - Or the appeal was filed within the time - Once the appellant had indicated in ST-IV form that the order was received by the appellant only on December 21, 2018, then it was for the Department to have controverted that the order had been received by the appellant earlier to this date and an explanation for the delay should not have been expected from the appellant. - since the appeal has been filed within the period of two months from the date of receipt of order by the appellant, the appeal cannot be dismissed by the commissioner (appeals) on the ground of delay iby calculating the period from the date of order - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932