Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
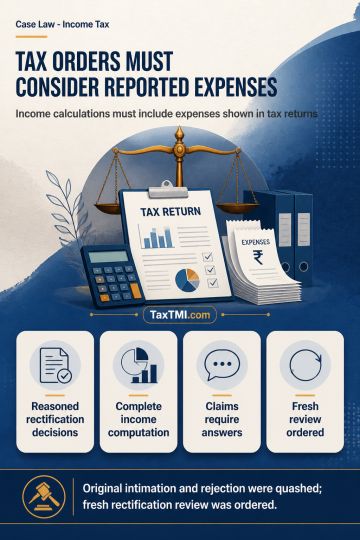
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Page of 4894
Press 'Enter' after typing page number.
61 to 80 of 97862 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Refund of Service Tax - principles of unjust enrichment - As per the work orders, service tax was to be borne by the appellant and the Commissioner (Appeals) has also found, as a fact, that the contract awarded by the Housing Board to the appellant mentions that service tax shall be borne by the contractor - Commissioner (Appeals) was, therefore, not justified in rejecting the refund claim of the appellant on the ground of unjust enrichment. - AT
Refund of Service Tax - principles of unjust enrichment - As per the work orders, service tax was to be borne by the appellant and the Commissioner (Appeals) has also found, as a fact, that the contract awarded by the Housing Board to the appellant mentions that service tax shall be borne by the contractor - Commissioner (Appeals) was, therefore, not justified in rejecting the refund claim of the appellant on the ground of unjust enrichment. - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894