Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
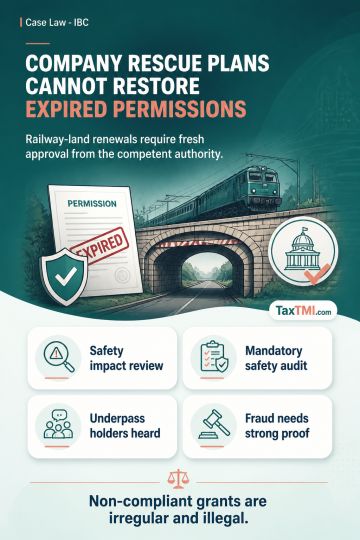
Way Leave Permissions cannot be retrospectively revived through insolvency plans, and affected infrastructure holders require safety review and hearin...
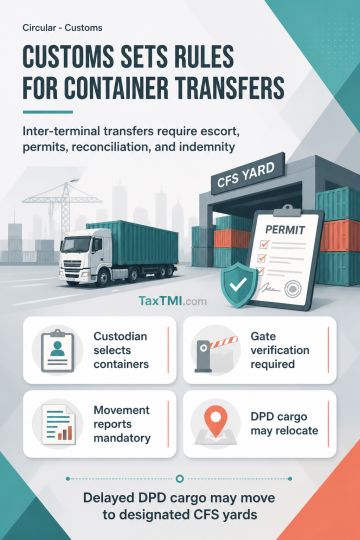
Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
Income deemed to accrue or arise in India - Chargeability of receipt from domain name registration as royalty under the domestic law as well as India-USA Double Tax Avoidance Agreement (DTAA) - the consideration received by the assessee from registration of domain names is in the nature of royalty under section 9(1)(vi) of the Act and is taxable as such - AT
Income deemed to accrue or arise in India - Chargeability of receipt from domain name registration as royalty under the domestic law as well as India-USA Double Tax Avoidance Agreement (DTAA) - the consideration received by the assessee from registration of domain names is in the nature of royalty under section 9(1)(vi) of the Act and is taxable as such - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899