Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
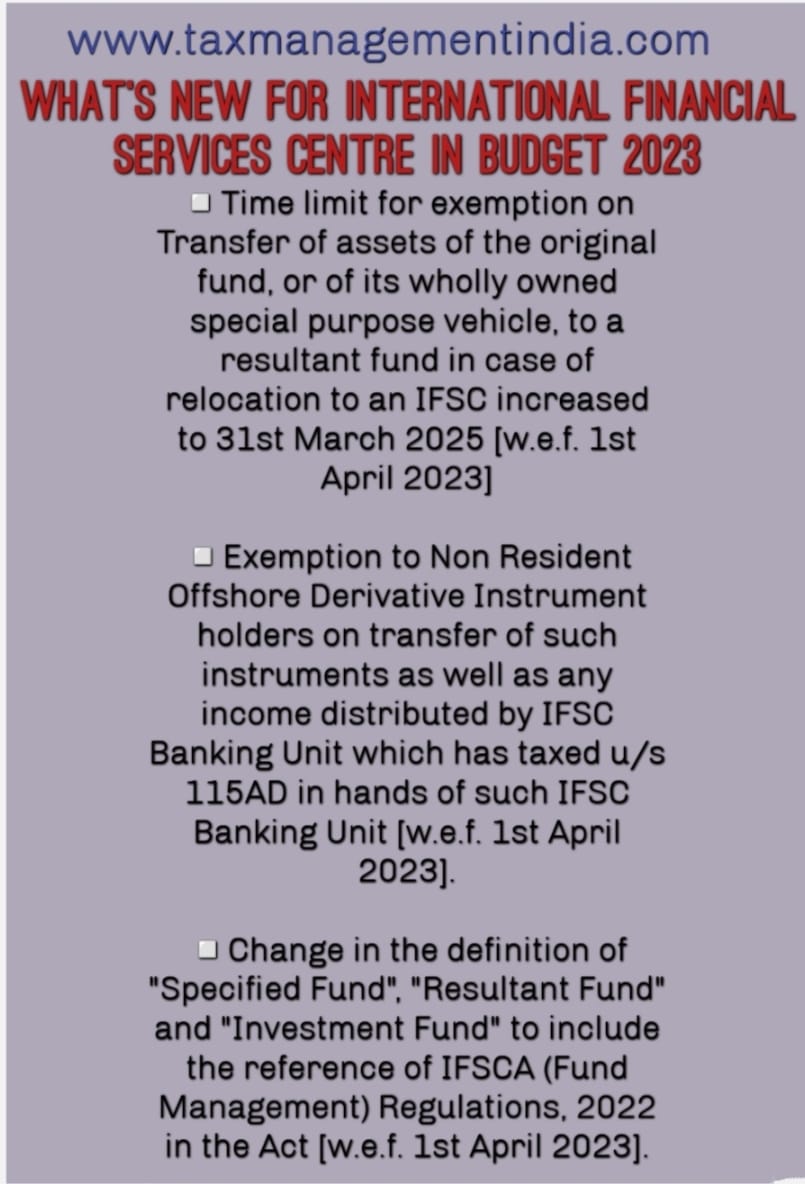
Tax Incentives to International Financial Services Centre - (i) Time limit for exemption on Transfer of assets of the original fund, or its wholly owned SPV to a resultant fund in case of relocation to an IFSC increased to 31st March 2025 [w.e.f. 1st April 2023] (ii) Exemption to Non Resident offshore derivative instrument holders on transfer of such instruments as well as any income distributed by IFSC Banking Unit ehich has taxed u/s 115AD in hands of such IFSC Banking Unit [w.e.f 1st April 2024] (iii) Change in the definition of 'Specified Fund', 'Resultant Fund', and 'Investment Fund' to include reference of IFSCA (fund Management) Regulations, 2022 in the Act [w.e.f. 1st April 2023].
Tax Incentives to International Financial Services Centre - (i) Time limit for exemption on Transfer of assets of the original fund, or its wholly owned SPV to a resultant fund in case of relocation to an IFSC increased to 31st March 2025 [w.e.f. 1st April 2023] (ii) Exemption to Non Resident offshore derivative instrument holders on transfer of such instruments as well as any income distributed by IFSC Banking Unit ehich has taxed u/s 115AD in hands of such IFSC Banking Unit [w.e.f 1st April 2024] (iii) Change in the definition of 'Specified Fund', 'Resultant Fund', and 'Investment Fund' to include reference of IFSCA (fund Management) Regulations, 2022 in the Act [w.e.f. 1st April 2023].
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881