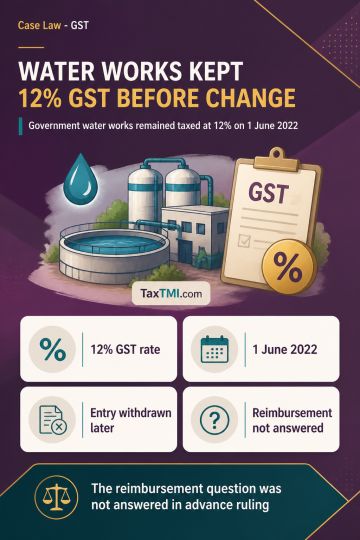
Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Page of 4899
Press 'Enter' after typing page number.
701 to 720 of 97973 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
LTCG - benefits of Section 54/54F - the nature and extent of construction or nomenclature like house, plot, cottage, farm house or villa are only indicative of the fact that property purchased is not a commercial property and is not an agricultural property. They all convey residential house property. How it is inhabited should not interest the revenue. - AT
Note: It is a system-generated summary and is for quick reference only.